From 1 December 2026, letting a furnished apartment or home in Spain for 30 nights or fewer to the same tenant carries IVA at 10%. Until now that let was exempt unless you offered hotel services. The change comes from article 7 of Real Decreto-ley 29/2026. The standing committee of Congress (Diputación Permanente) confirmed the decree on 12 November 2026 by 35 votes to 34, so the change goes ahead.
In short: 30 nights or fewer pay 10% IVA. More than 30 nights with the same tenant stays exempt. The home where you live stays exempt. If your lets carried no IVA until now, you have to file modelo 036 before your first let with IVA. After that you invoice each stay and file modelo 303 every quarter. Each rule comes with its article.
What changed and from when
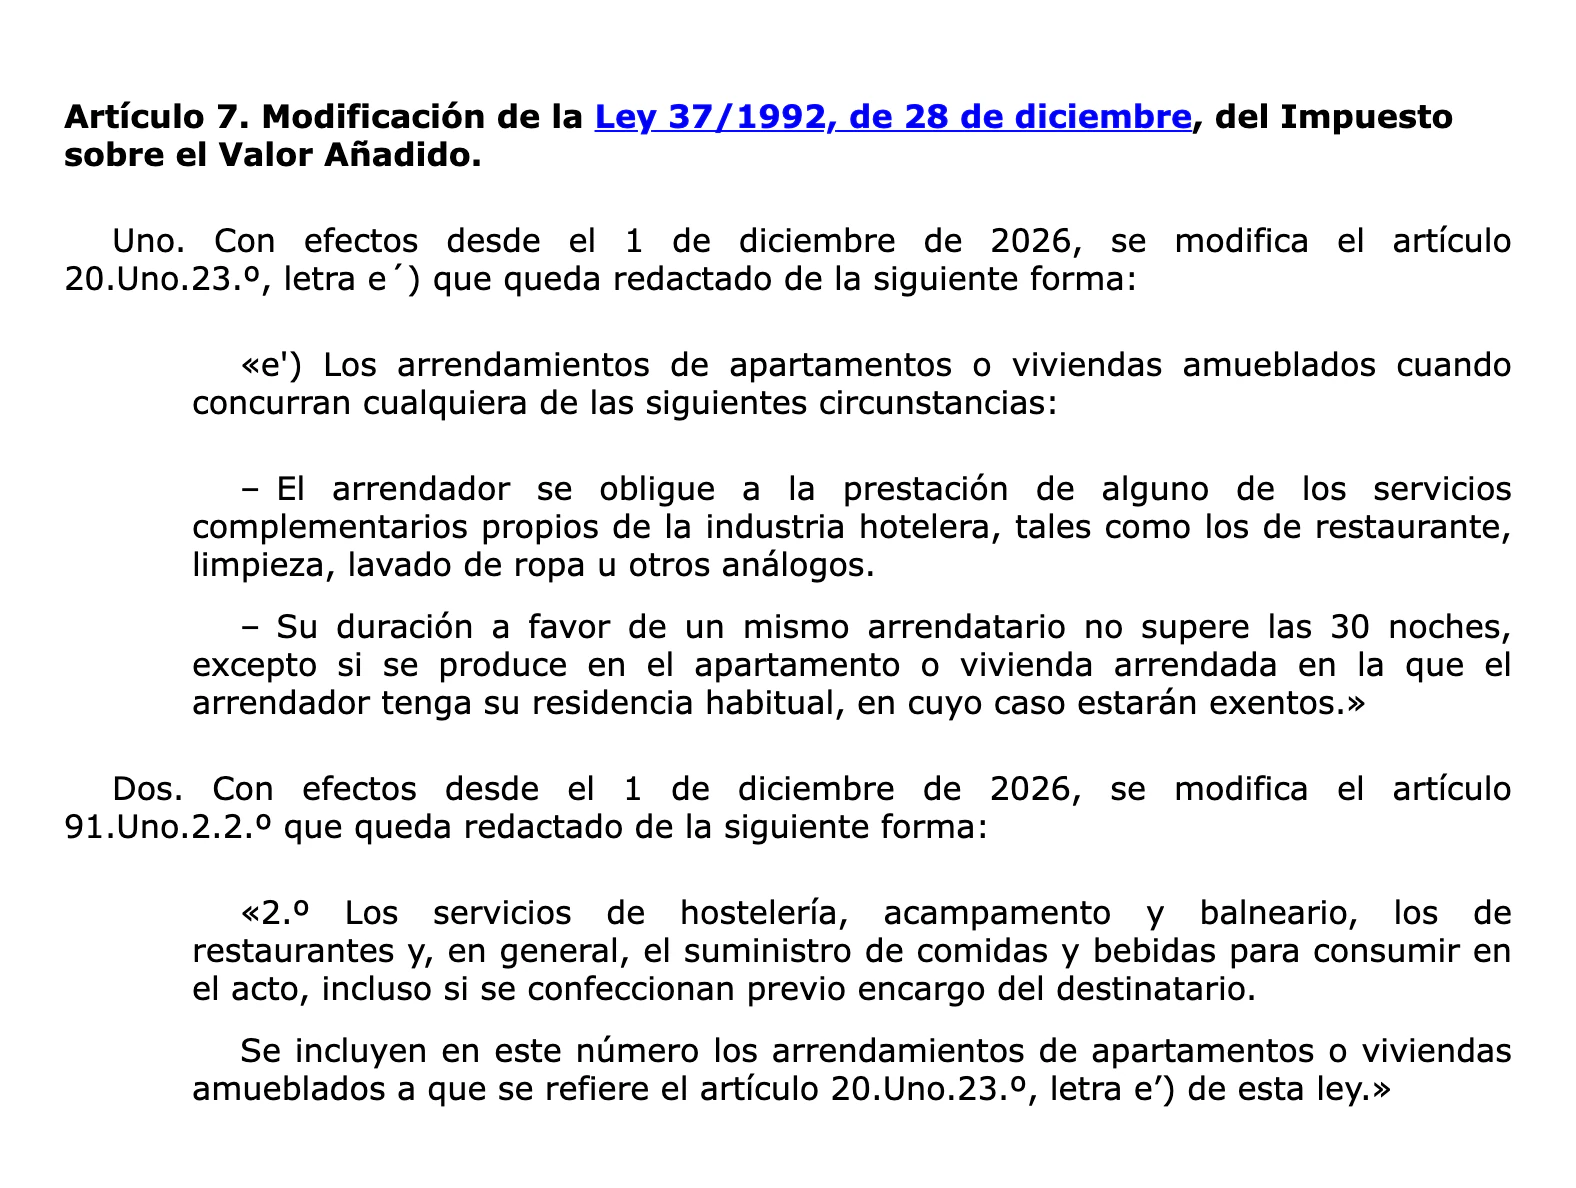
The IVA Law exempts the letting of buildings used as homes (article 20.Uno.23.º b of Ley 37/1992). The same rule lists the lets that fall outside that exemption. One of them, under letter e'), was the furnished apartment or home let with hotel services. Article 7 of Real Decreto-ley 29/2026 adds a second case to that letter: a let that lasts 30 nights or fewer for the same tenant.
The same article moves those lets to the reduced rate, 10% (article 91.Uno.2.2.º of the IVA Law). Both changes take effect on 1 December 2026.
The decree was published in the BOE on 7 October 2026 and has been in force since the next day. A decree-law also needs Congress to confirm it. With parliament dissolved ahead of the election of 29 November, its standing committee voted on 12 November. A second decree, 28/2026, on the length of rental contracts, was voted down the same day. That one did not touch IVA.
| Let | IVA from 1 December 2026 | Where it says so |
|---|---|---|
| Furnished home, 30 nights or fewer with the same tenant | 10% | Article 20.Uno.23.º e') and article 91.Uno.2.2.º |
| More than 30 nights with the same tenant | Exempt, as before | Article 20.Uno.23.º b) |
| The home where you live, 30 nights or fewer | Exempt | Article 20.Uno.23.º e') |
| With hotel services: restaurant, cleaning, laundry | 10%, as before | Article 20.Uno.23.º e') and article 91.Uno.2.2.º |
Which lets stay exempt
The change only reaches short stays in furnished homes. Three cases stay as they were:
- More than 30 nights with the same tenant. The law counts how long the let lasts for one tenant. At 30 nights there is IVA. At 31 the let stays exempt.
- The home where you live. If you let a room in your home, or the whole place for the weeks you are away, the let is exempt even for a few nights. The law says a short let is exempt when it takes place in the home where the landlord has their habitual residence.
- The usual rental. The flat you rent out by the month or the year to the person who lives in it does not change.
What already carried IVA still does. If you commit to hotel-type services, such as a restaurant, cleaning or laundry, the let carries 10% however long it lasts.
How much it is: an example with numbers
Marta lets her beach apartment for five nights at €100 a night. From 1 December she has two options:
- Keep the price the guest pays. The guest pays €500. Of that, €454,55 is the base and €45,45 is IVA. Marta keeps €45,45 less than before.
- Add the IVA to the price. The base stays at €500, the IVA is €50 and the guest pays €550.
Either way the IVA is not Marta's. She collects it from the guest and pays it to Hacienda with the quarter's modelo 303.
Bookings you have already been paid for
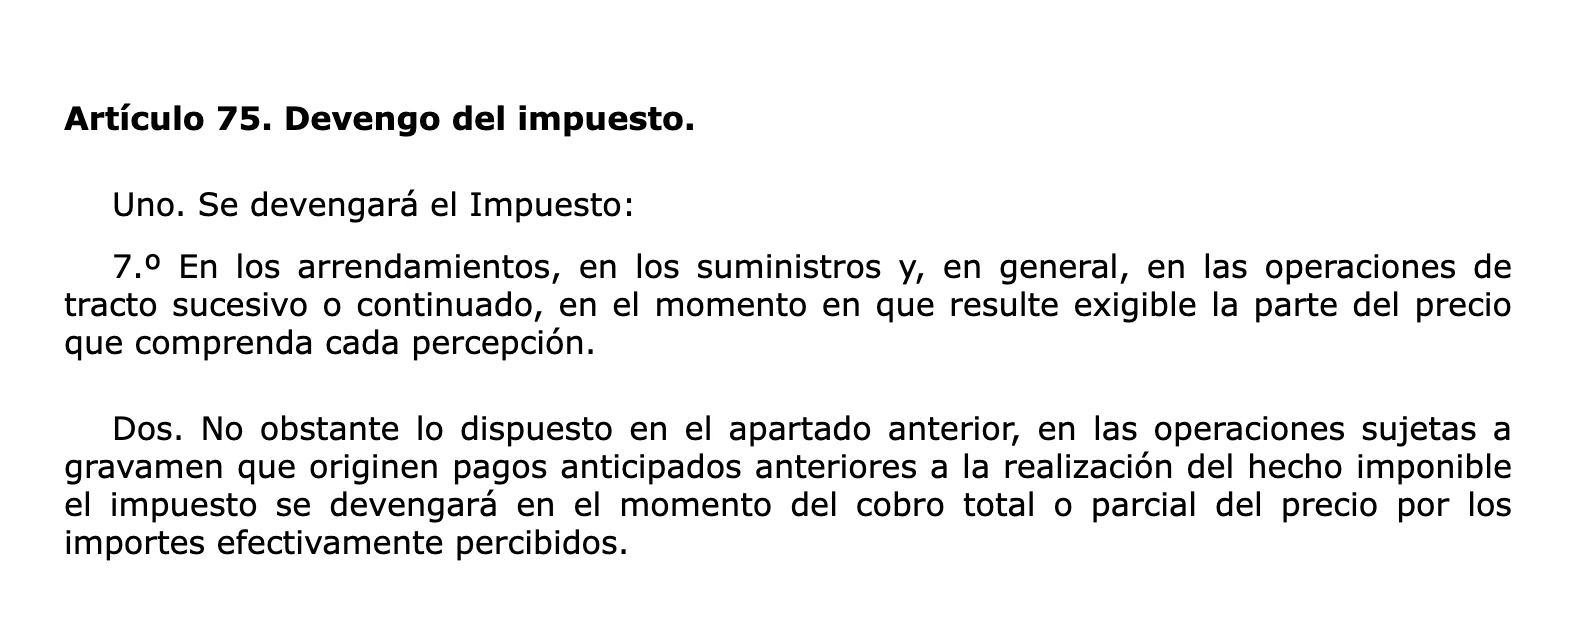
IVA does not look at the booking date or the check-in date. On a let, the tax accrues when each part of the price falls due (article 75.Uno.7.º of the IVA Law). If you are paid in advance, it accrues on the day you are paid, on the amount received (article 75.Dos). The rate is the one in force that day (article 90.Dos).
The decree brings no transitional rule for IVA, so those general rules apply. An example: in November you take a €150 deposit for a December stay and the remaining €350 on arrival. The deposit accrued in November, when the let was exempt. The €350 accrues in December and carries 10% IVA.
What you have to do before 1 December
If you already file IVA for another activity, only the rate on your short-stay invoices changes. If your only lets were exempt until now, you have three new duties (article 164.Uno of the IVA Law):
- File modelo 036. A landlord whose lets are all exempt is not on Hacienda's register of businesses (article 3.2.a of Real Decreto 1065/2007). With lets that carry IVA you have to be on it. The form is filed before you start, that is, before your first let with IVA (article 9.4). The modelo 036 guide explains it.
- Invoice each stay. An exempt let to a private person needed no invoice (article 3.1.a of Real Decreto 1619/2012). A let with IVA does, including what you are paid in advance (article 2.1). Up to €400 with IVA included, a simplified invoice is enough (article 4.1.a).
- File modelo 303 every quarter. The first one with this IVA is for the fourth quarter of 2026, filed from 1 to 30 January 2027 (article 71.4 of Real Decreto 1624/1992). The modelo 303 guide has the steps.
There is an upside. The IVA on what you buy for those lets becomes deductible to the extent you use it for lets that carry IVA (article 94 of the IVA Law). If you also have exempt lets, a long-term one for example, you deduct only part of it under the pro rata rule (article 102).
If you let through a platform
You are the one letting the home, not the platform. The invoice to the guest is yours and covers the full price they pay, IVA included. The commission the platform charges you is a separate expense with its own invoice.
To go over how the tax works before you start, read the guide to IVA in Spain.