Many yoga and pilates teachers teach for a studio, a gym or a hotel and send them an invoice every month. So do many trainers. That invoice has two things a student's does not: the business's tax ID and income tax (IRPF) withheld, which the business pays to Hacienda on your behalf.
Here is how it works, with an example and each article. If you also have your own students and want them to book and pay on your page, see Bookings for pilates and yoga teachers.
A full invoice, with the business's tax ID
When the client is a business or a professional, an invoice is always required (article 2.2.a of Real Decreto 1619/2012). As a rule it is a full one: with the business's name and tax ID (NIF) as well as yours (article 6), because the business uses it to deduct the IVA. Up to €400 a simplified invoice also works, if it carries the business's NIF and address and the IVA shown separately (articles 4.1.a and 7.2).
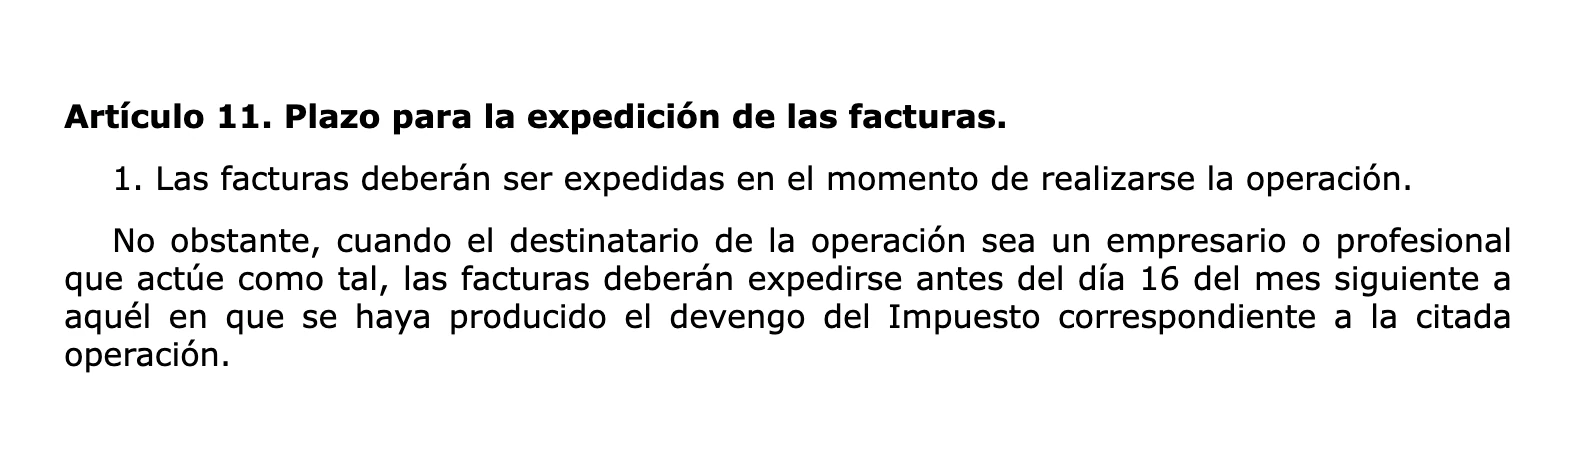
The deadline changes too. For a business client, the invoice is issued before the 16th of the month after the one in which you taught (article 11.1). November's classes are invoiced by 15 December at the latest.
IVA: 21%, as with your students
A business paying does not change the rate. Your classes carry 21% (article 90 of the IVA Law). Spain's tax directorate (Dirección General de Tributos) confirmed it for a self-employed trainer invoicing gyms in ruling V0759-26 of 6 April 2026. The reasons are in IVA on yoga and pilates classes.
Income tax withholding: 15% or 7%
A business that pays you as part of its activity has to withhold income tax (article 76.1 of the IRPF Regulation). Teaching at the student's home or in premises that are not yours is a professional activity (article 95.2.b.3.º), as are the activity codes of group 826 and of the sport grouping 04. The rate is:
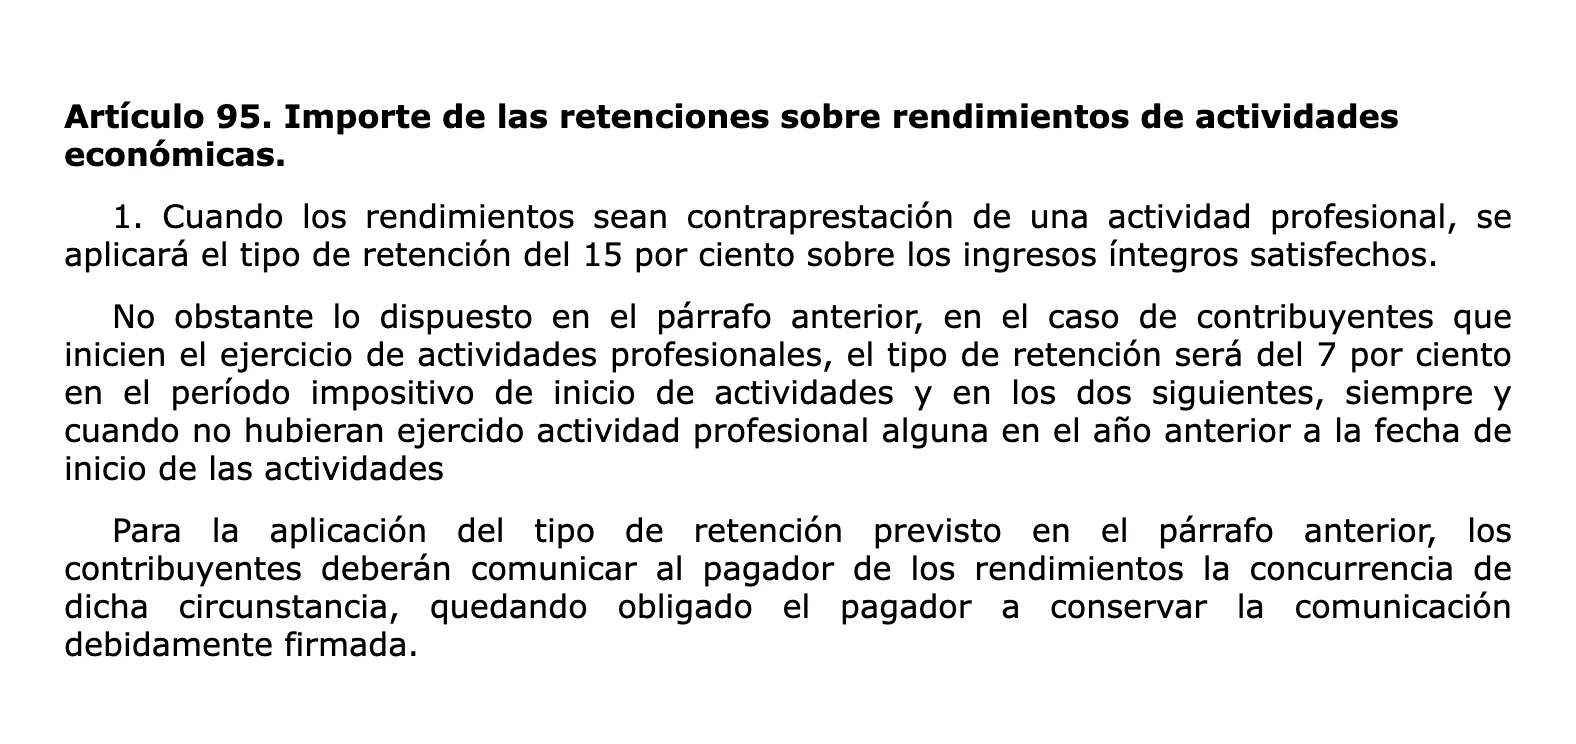
- 15% as a rule (article 95.1).
- 7% in the year you start and the two after, if you had no professional activity the year before. You have to tell the business that pays you in writing.
Withholding is worked out on the base, without IVA. The business pays it to Hacienda on its modelo 111 and you subtract it on your instalments and your income tax return: it is not money lost. We cover it in income tax withholding on your invoices.
An example with numbers
Elena teaches 8 yoga classes a month at a studio, at €40 each. She has been self-employed for two years, so she applies 15%:
| Item | Amount |
|---|---|
| 8 yoga classes in November, at €40 | €320,00 |
| IVA at 21% | €67,20 |
| Income tax withheld at 15% | -€48,00 |
| Total the studio pays you | €339,20 |
The €67,20 of IVA you declare on your modelo 303. The studio pays in the €48,00 for you. It counts as already paid on your income tax.
Modelo 130, if nearly everything has withholding
If in the previous year at least 70% of your professional income had withholding, you do not have to file modelo 130 (article 109.2 of the IRPF Regulation). If you teach nearly all your classes for studios and gyms, that may be you. If most of your income comes from your own students, you keep filing it. The steps are in the modelo 130 guide.