If you teach yoga or pilates on your own account on a regular basis in Spain, you are an autónomo, self-employed: you carry out an economic activity regularly, personally and directly, on your own account (article 1.1 of Ley 20/2007). It makes no difference whether you teach in a rented room, in a park, in a hotel or by video call.
What does change with where and for whom you teach is your activity code, the withholding and the forms. Here it is step by step. If you want your students to book their spot on your own page, see Bookings for pilates and yoga teachers.
The two registrations
Before your first class you register with Hacienda on modelo 036 (article 9 of Real Decreto 1065/2007) and with the Seguridad Social as self-employed. If it is your first registration, or you have not been registered for two years, you can ask for the reduced contribution for the first twelve months on the same application (article 38 ter of Ley 20/2007). If you already had the reduced contribution in your previous registration, you need three years without being registered (article 38 ter.4). The modelo 036 and tarifa plana guides have the details.
Your activity code: professional or business
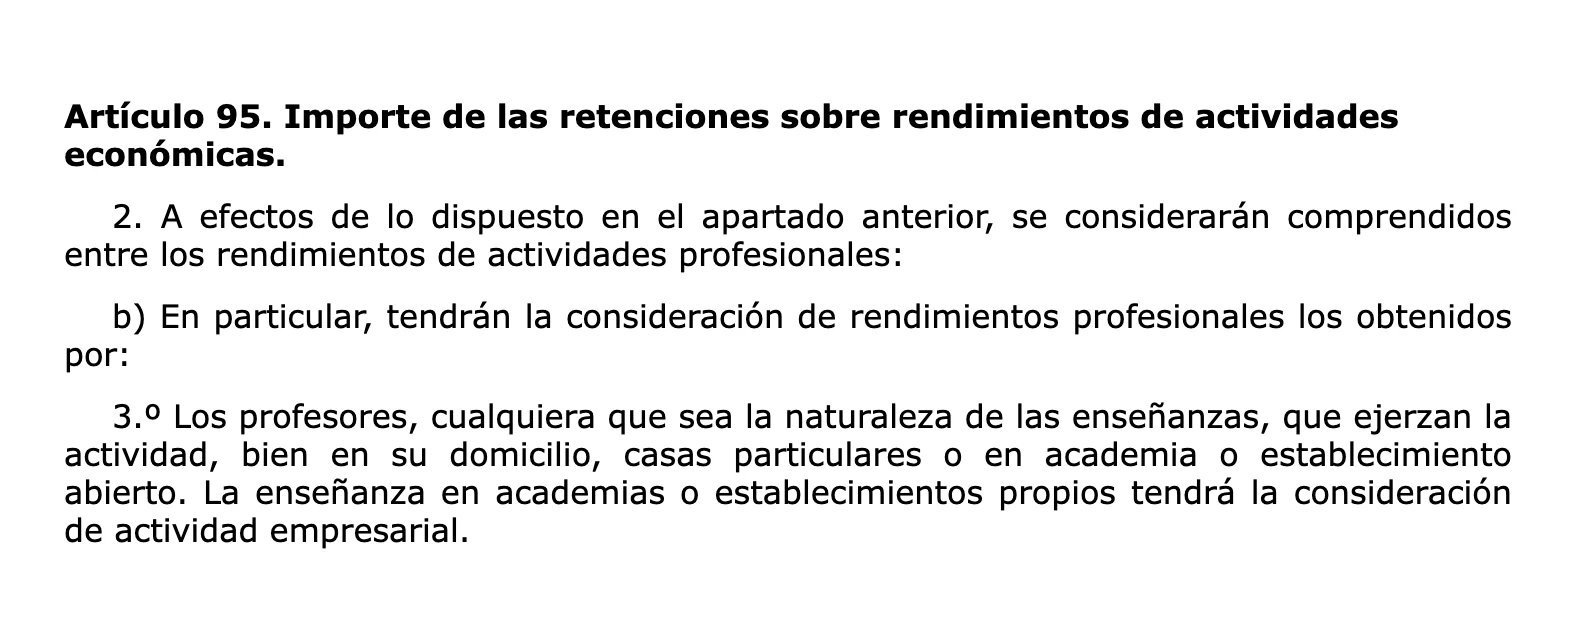
The IRPF Regulation separates two situations (article 95.2.b.3.º):
- You teach at your home, at your students' homes or in premises that are not yours, such as a studio, a gym or a room you rent by the hour. It is a professional activity. Your code is usually group 826 of section two, teachers of various subjects.
- You open your own studio. Teaching in your own academy or premises is a business activity, with a code from section one.
The difference matters for withholding: only professional activities carry income tax withholding when you invoice a business. There is more help in how to choose your activity code.
Your students and the studios: two kinds of invoice
Almost every teacher does both. The classes carry 21% IVA either way, as we explain in IVA on yoga and pilates classes. What changes is the invoice:
| Your own students | A studio, gym or hotel | |
|---|---|---|
| Invoice | Simplified up to €400 | Full, with their tax ID |
| Income tax withheld | No | 15%, or 7% when starting |
| When | When you are paid | Before the 16th of the following month |
We explain the invoice to a studio with an example in teaching for a studio, a gym or a hotel. And if you sell packs to your students, see yoga and pilates class packs.
The forms every quarter
Every quarter you file modelo 303 with the IVA on your classes minus the IVA on what you buy for work: the mat, the props, the room you rent, your training courses. The modelo 303 and deductible expenses guides help with both parts.
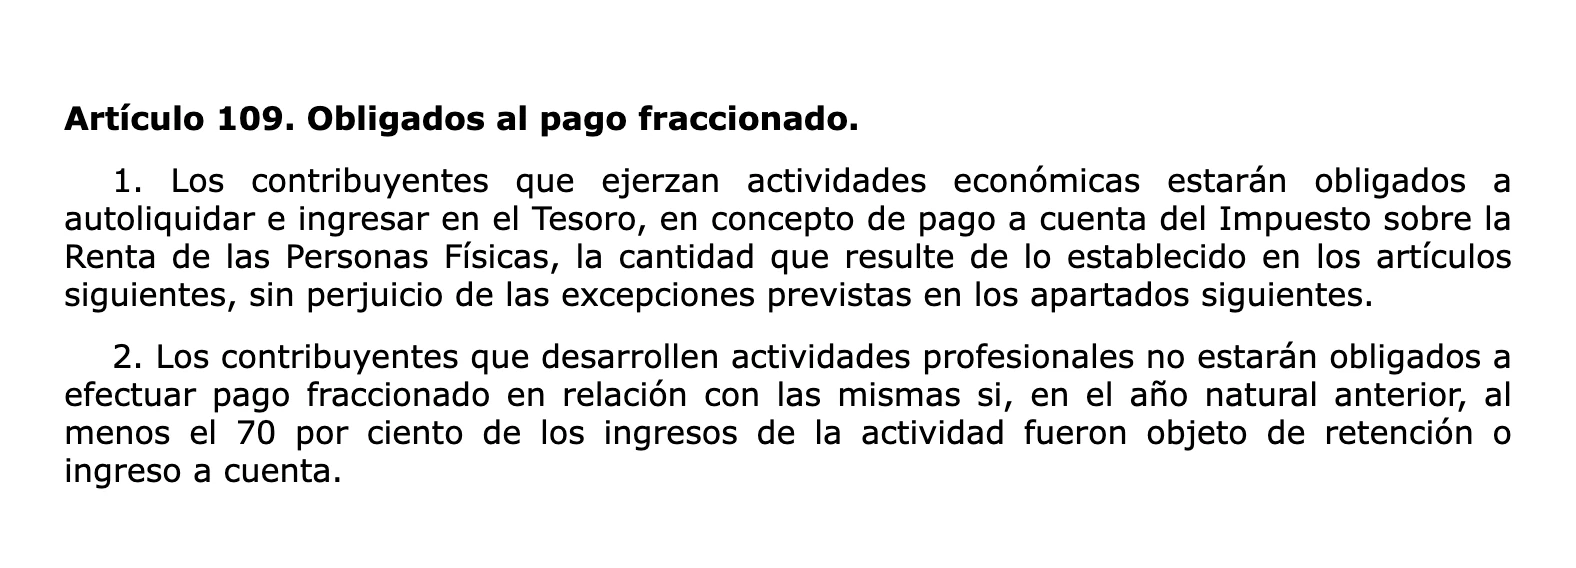
Modelo 130 depends on the mix. If in the previous year at least 70% of your income had withholding, you do not file it (article 109.2 of the IRPF Regulation). If you teach nearly all your classes for studios, that may be you. If most of your income comes from your students, you file it every quarter.
If a studio employs you
If you also have an employment contract with a studio or a gym, you can be self-employed and employed at the same time. It is called pluriactividad and we cover it in pluriactividad. If you would rather we did your registrations, our team handles your autónomo registration with Hacienda and the Seguridad Social.