You have an employment contract and want to invoice on your own account in the evenings, or you are an autónoma (self-employed woman) and you are offered a part-time job. You can do both at once. Social Security calls this pluriactividad (multiple activity): you are registered in the Régimen General (the general scheme for employees) through your payslip and in the RETA, the self-employed scheme, through your business. Each scheme charges its own contributions, although the law refunds part of them if you pay a lot across the two.
Registering as an autónomo is the same as for anyone else and you have it step by step in how to become an autónomo in Spain. Here we cover what changes because you also have a payslip: what you pay, when you get contributions back, whether you get the tarifa plana, what happens with sick leave and how you file your income tax.
What pluriactividad is
It is the situation of someone who works both on their own account and as an employee and must therefore be registered in two different Social Security schemes (article 7.4 of Real Decreto 84/1996). You register in each scheme, each with its own rules (article 41 of the same regulation). It is not the same as pluriempleo, which means working as an employee for two companies within the same scheme.
You do not need your employer's permission to register as an autónomo, but read your contract. The Workers' Statute (Estatuto de los Trabajadores) does not let you work for others if that means unfair competition with your employer or if you agreed full-time exclusivity with them in exchange for financial compensation (article 21.1).
You contribute to both schemes
Through your payslip you contribute to the Régimen General as usual: your employer pays its share and yours, which it deducts from your salary. Through your business you pay the autónomo contribution, which is set by brackets according to your net earnings for the year (article 308 of the General Social Security Law, Ley General de la Seguridad Social or LGSS).
Your salary does not count towards that bracket. The law only adds up the earnings from your business or professional activities and leaves out those for which you are registered as an employee (article 308.1). Having a payslip does not lower the contribution either: you choose your base like any autónomo and the following year it is adjusted with the tax agency's figures. We explain it in Social Security contributions for autónomos and in the annual adjustment of the autónomo contribution.
Until 2022 the law let people starting in pluriactividad choose lower bases, of 50% and 75% of the minimum base. Real Decreto-ley 13/2022 removed those bases from 01/01/2023, so they no longer exist.
Sick leave cover is optional in the RETA
Cover for incapacidad temporal (temporary incapacity, meaning sick leave) is compulsory in the RETA unless you already have it through your activity in another scheme. In that case it is optional: you can opt in and you can also give it up (article 315 LGSS). The rules are in article 47.3 of Real Decreto 84/1996:
- You can opt in when you register as an autónomo, from the date of registration, or later by applying before 1 October of any year, with effect from 1 January of the following year.
- You can give it up before 1 October of any year, with effect from the next 1 January. If you were already an autónomo and you start a job, you can give it up within 30 days of being registered in that job, with effect from the first day of the following month.
- If you are an economically dependent autónomo (TRADE), the cover is compulsory even in pluriactividad.
If you do not have sick leave cover in the RETA, your common contingencies contribution is reduced: it is multiplied by a reduction coefficient of 0,055 and that amount is taken off (article 18.2.a of Orden PJC/297/2026). Cover for work accidents and occupational diseases remains compulsory (article 316.1 LGSS). What you receive if you fall ill is in sick leave for autónomos.
The refund if you contribute too much across the two
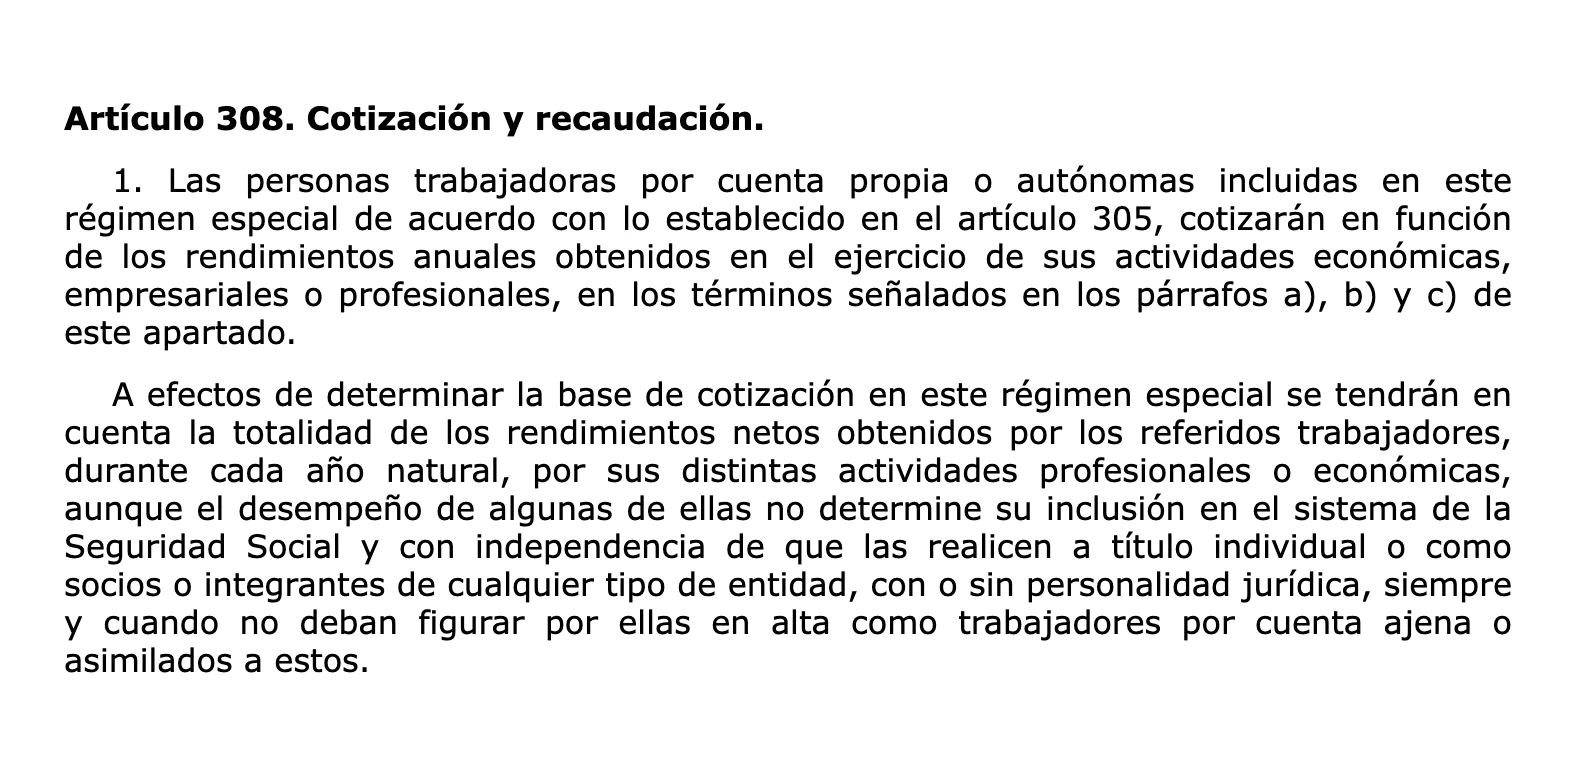
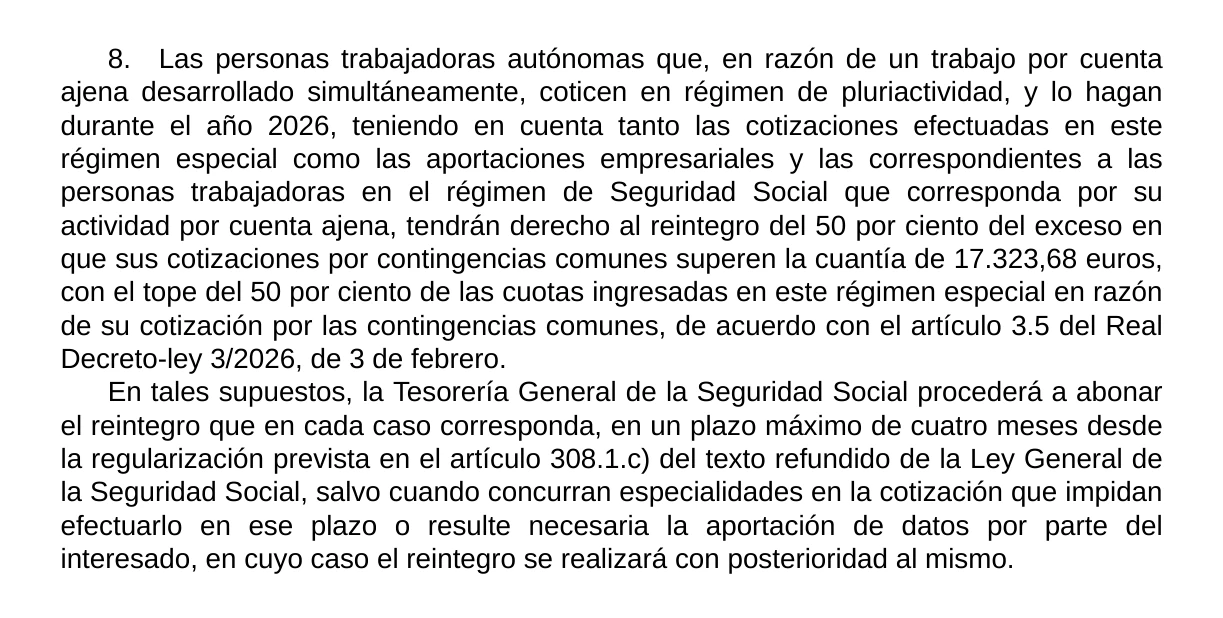
If the common contingencies contributions paid for you in both schemes pass a figure set each year, the Social Security Treasury (Tesorería General de la Seguridad Social) refunds 50% of the excess (article 313 LGSS). Everything counts: your autónomo contribution for common contingencies, your employer's share and the share you pay through your payslip.
- The 2026 figure is €17.323,68 (article 3.5 of Real Decreto-ley 3/2026 and article 18.8 of Orden PJC/297/2026).
- The cap: the refund cannot exceed 50% of what you paid into the RETA for common contingencies.
- When: the Treasury pays it within four months of the annual adjustment of your autónomo contribution at the latest. It can take longer if your contributions have special features or if it needs information from you.
An example
Marta has a payslip with a common contingencies contribution base of €50.000 a year. As a self-employed designer she contributes all of 2026 on €1.274,51 a month, the minimum base of general bracket 6. She also has sick leave cover in the RETA. We assume the annual adjustment does not change her base. The common contingencies rate is 28,30% in both schemes: on the payslip the employer pays 23,60% and she pays 4,70% (articles 18.2 and 4 of Orden PJC/297/2026).
| Item | Amount |
|---|---|
| Payslip: 28,30% of €50.000 | €14.150,00 |
| RETA: 28,30% of €1.274,51 = €360,69 a month, for 12 months | €4.328,28 |
| Total common contingencies contributions | €18.478,28 |
| Excess over €17.323,68 | €1.154,60 |
| 50% of the excess | €577,30 |
| Cap: 50% of what she paid into the RETA | €2.164,14 |
Marta receives €577,30 after the adjustment of her 2026 contributions. With a lower salary there would be no refund: the total would not reach the figure for the year.
The tarifa plana also applies in pluriactividad
The reduced start-up contribution looks at your history in the RETA, not at whether you have a payslip. You are entitled to it if it is your first registration as an autónomo or you have not been registered in the previous two years, three if you have had it before (article 38 ter of Ley 20/2007). The law does not exclude people who are also employed.
You apply for it when you register and it lasts 12 full calendar months, plus another 12 if your net earnings for the year stay below the minimum wage (salario mínimo interprofesional). During the first 12 months you do not contribute for cese de actividad (the autónomo unemployment benefit) or for vocational training (article 38 ter.1). On the amount: until 2025 it was set by Real Decreto-ley 13/2022 and from 2026 it is set by the State Budget Law, which has not been passed as of the date of this article, so check the amount when you apply. The details are in what the tarifa plana is and how to apply.
With the tax agency: two incomes and one Renta
Your salary is employment income and what you invoice is business income. Both go into the general base of IRPF (personal income tax) and are taxed together on the progressive scale you can see in the 2026 IRPF bands. This has practical consequences:
- You always file the Renta (the annual income tax return). Anyone registered in the RETA at any point in the year must file, whatever they earn (article 96.2 of Ley 35/2006 on IRPF). We cover it in the Renta for autónomos.
- The withholding on your payslip does not know you invoice. Your employer works it out from your salary. Because both incomes are added together on the scale, the Renta often ends with an amount to pay if you have not paid enough in advance for your business.
- Your invoices to businesses and professionals carry withholding if your activity is a professional one: 15%, or 7% in the year you start and the two following years if you carried out no professional activity in the previous year (article 95.1 of the IRPF Regulation). Your job is not a professional activity. More in IRPF withholding on your invoices.
- Modelo 130 pays in advance each quarter 20% of your cumulative net earnings for the year (article 110.1.a of the Regulation). If you are a professional and in the previous year at least 70% of your business income had withholding, you do not have to file it (article 109.2). In your first year the percentage of the quarter itself is used (article 109.5). You have it in modelo 130.
Your business also charges IVA (VAT) like any autónomo's, with modelo 303 every quarter.
Common mistakes
- Thinking that with a payslip you do not pay the autónomo contribution. You pay in both schemes.
- Expecting the refund in spring. Since 2023 it comes after the adjustment of your contributions, which uses the tax agency's figures the following year.
- Letting 1 October go by without deciding whether you also want sick leave cover in the RETA.
If you run your business with Facturaz, your invoices, expenses and quarterly modelos come from what you record: with Autónomo Go (€24 + IVA a month) you file them yourself with everything ready and with Autónomo Plus (€44 + IVA a month) our team files them. You have 14 days free on the Facturaz plans. The refund of contributions is paid by the Treasury and does not go through us.