Many studios rent out the room by the hour in the gaps of their schedule: to a yoga teacher giving her own class, to a physiotherapist, to someone running a Saturday workshop. That rental carries 21% IVA. The question is whether it also carries income tax withholding. That depends on what you rent out: just the room, or the room with services.
Here are both cases, with their articles and an example. If you want to see on your studio's agenda who teaches each hour, see Bookings for pilates and yoga studios.
IVA: 21%
The IVA Law only exempts renting buildings used exclusively as homes (article 20.Uno.23.º b of Ley 37/1992). A room for teaching is not a home, so renting it goes at the standard 21% (article 90).
Is there withholding? It depends on what you rent out
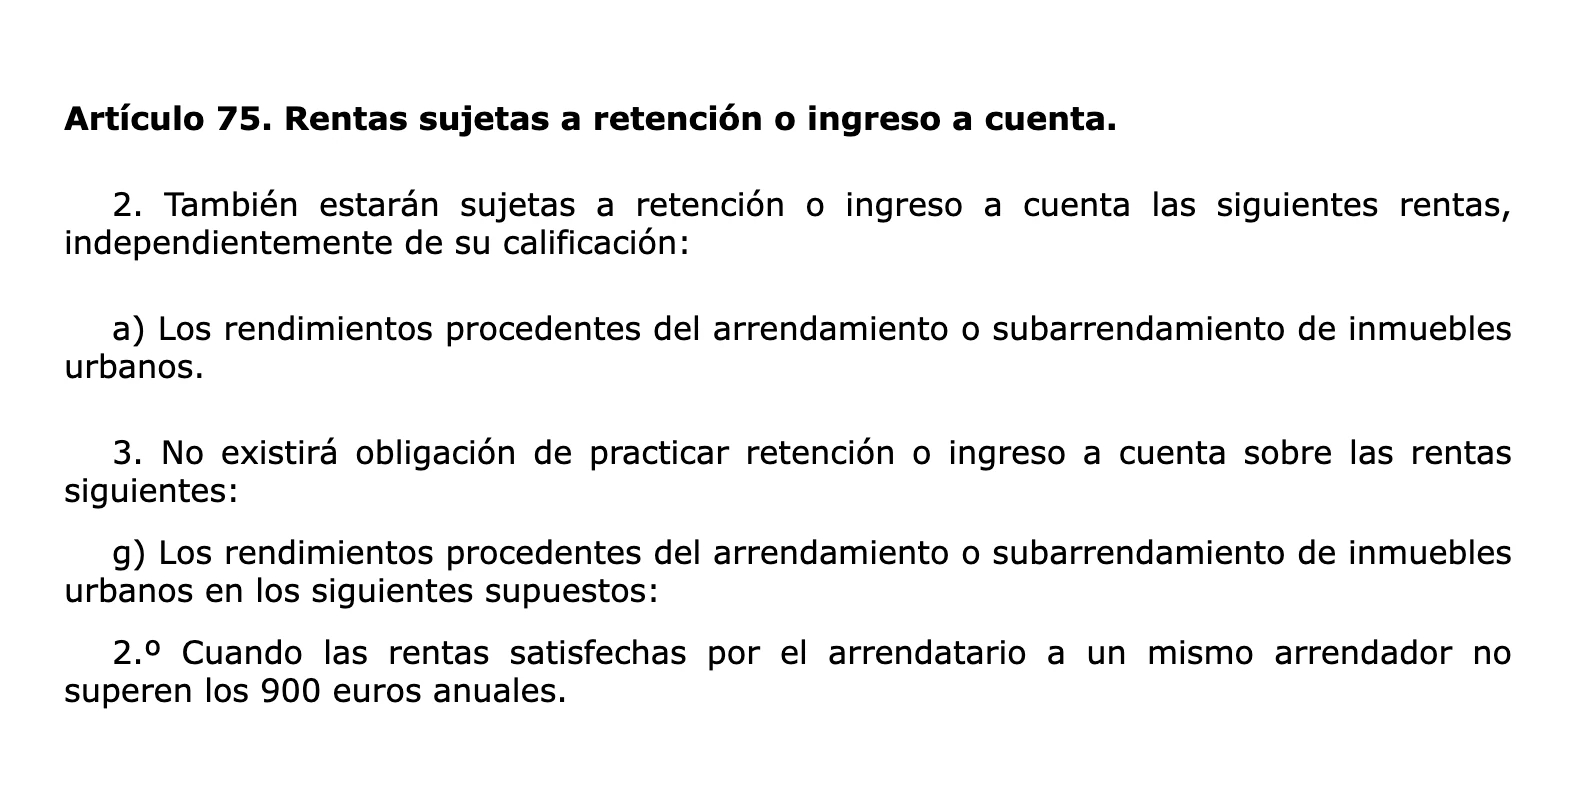
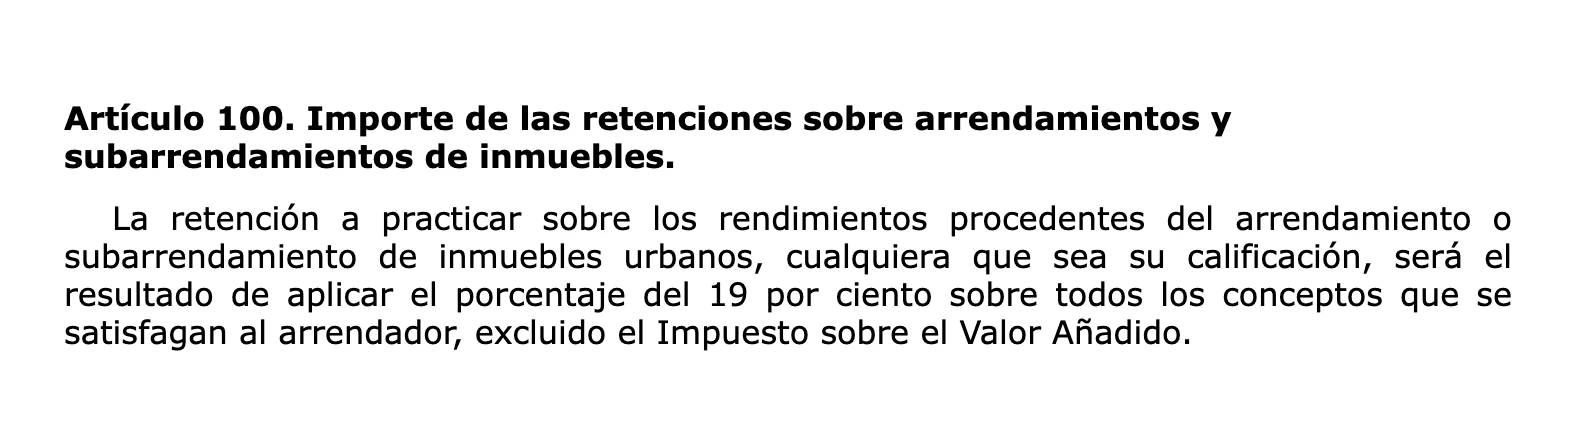
Renting urban premises is subject to income tax (IRPF) withholding, however it is classed (article 75.2.a of the IRPF Regulation). Withholding is 19% of everything paid to the landlord, IVA excluded (article 100). The tenant applies it when they are a business or an autónomo renting for their activity (article 76.1).
But if you provide services with the room, Spain's tax directorate (Dirección General de Tributos) treats it differently. In ruling V1461-20, on a desk in a coworking space with cleaning, secretary and utilities, it says it is a mixed contract of rental and services, which goes beyond a simple rental and carries no withholding. In ruling V0618-21 it reached the same answer for a physiotherapist who let their premises some days and hours a week, with its infrastructure and staff.
Both cases had staff: a secretary or a receptionist. It is not clear that cleaning or utilities alone are enough to stop it being a rental, so treat it as a rental, with its 19% withholding.
| What you rent out | IVA | Income tax withholding |
|---|---|---|
| Just the room, to a self-employed teacher | 21% | 19% (articles 75.2.a and 100) |
| The room with staff, such as reception or a secretary, as well as cleaning or utilities | 21% | No, it is a mixed contract (rulings V1461-20 and V0618-21) |
| The room with cleaning or utilities, no staff | 21% | Treat it as a rental: 19% |
| Just the room, for no more than €900 a year to the same tenant | 21% | No (article 75.3.g.2.º) |
Put in writing what the rental includes. If you provide mats, reformers, cleaning or someone at reception, have it in the agreement.
An example with numbers
Lucía rents your room 8 hours a month, at €20 an hour, for her hypopressive classes. Just the room:
| Item | Amount |
|---|---|
| 8 hours of room in November, at €20 | €160,00 |
| IVA at 21% | €33,60 |
| Income tax withheld at 19% | -€30,40 |
| What Lucía pays you | €163,20 |
You declare the €33,60 of IVA on your modelo 303. Lucía pays the €30,40 to Hacienda on your behalf. You subtract it on your instalments and your income tax return. If the room came with services, there would be no withholding and Lucía would pay you €193,60.
Modelo 115 and 180, for whoever withholds
Whoever withholds declares and pays it every quarter on modelo 115, in the first 20 days of April, July, October and January (article 108.1 of the IRPF Regulation). The year is summarized on modelo 180 (article 108.2). If you are the one renting a room to teach your classes, that is you. The steps are in the modelo 115 and modelo 180 guides.
If instead of renting them the room you pay teachers to teach at your studio, the rules are different: we explain them in paying self-employed teachers at your studio.
With Bookings each person has their own column on the agenda, by day or by week, so you see who uses the room and when.