If self-employed teachers teach at your studio, each one sends you an invoice with IVA and you withhold part of it as income tax (IRPF). That withholding is not yours: you pay it to Hacienda on their behalf every quarter, on modelo 111. In January you summarize the year on modelo 190 and give each teacher a certificate of what you withheld.
Here is each duty with its article and an example with numbers. If you want clients to book with the teacher they prefer, each with their own column on the agenda, see Bookings for pilates and yoga studios.
What the teacher invoices you
A teacher who teaches at your studio, which is not theirs, carries out a professional activity (article 95.2.b.3.º of the IRPF Regulation). Their invoice to your studio is a full one, with your tax ID (article 6 of Real Decreto 1619/2012). It carries 21% IVA and the income tax withholding. They have to issue it before the 16th of the month after the classes (article 11.1).
How the teacher writes it, seen from their side, is in teaching for a studio, a gym or a hotel.
Withholding: 15% or 7%
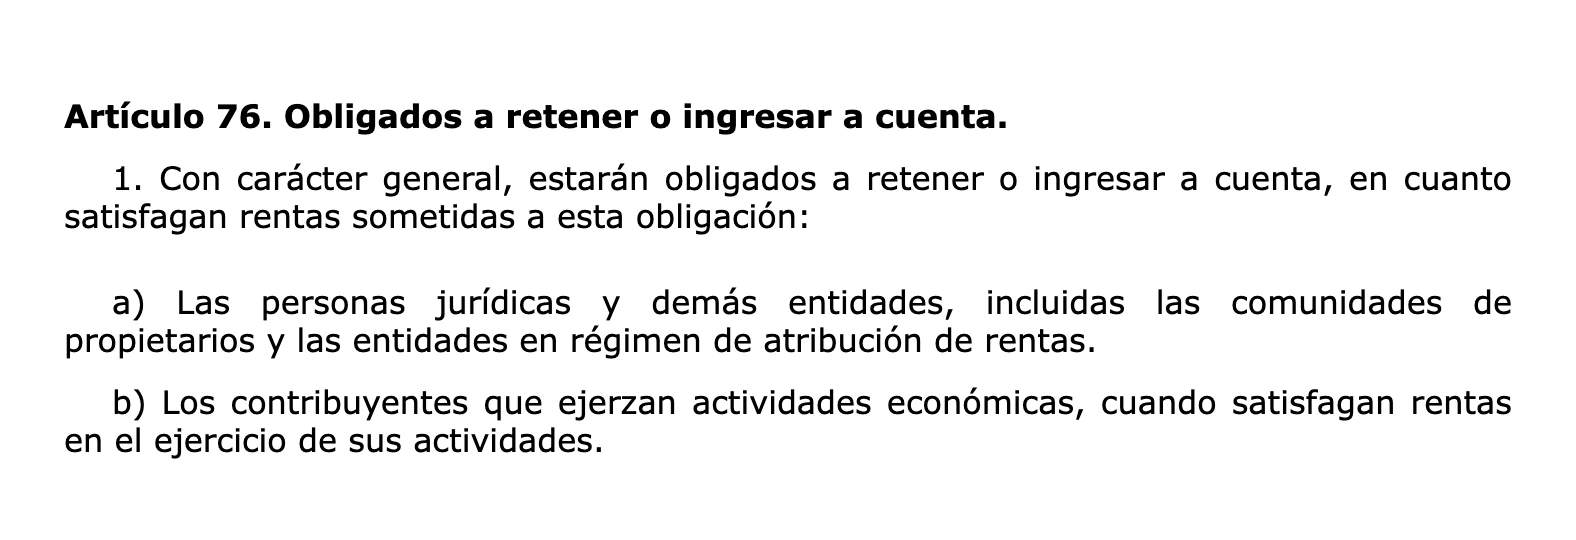
As a business or autónomo paying as part of your activity, you have to withhold (article 76.1 of the IRPF Regulation). The rate is 15% of the base, without IVA (article 95.1). It is 7% if the teacher is in their start year or the two after and had no professional activity the year before. To apply 7%, the teacher has to tell you in writing. Keep that notice.
An example with numbers
Marta teaches 12 reformer classes a month at your studio, at €35 each. She has been self-employed for five years:
| Item | Amount |
|---|---|
| 12 classes in October, at €35 | €420,00 |
| IVA at 21% | €88,20 |
| Income tax withheld at 15% | -€63,00 |
| What you pay Marta | €445,20 |
You pay the €63,00 to Hacienda on the fourth-quarter modelo 111. The €88,20 of IVA you subtract on your modelo 303, because you use those classes to give classes that carry IVA (articles 92 and 94 of the IVA Law).
Modelo 111 every quarter, 190 in January
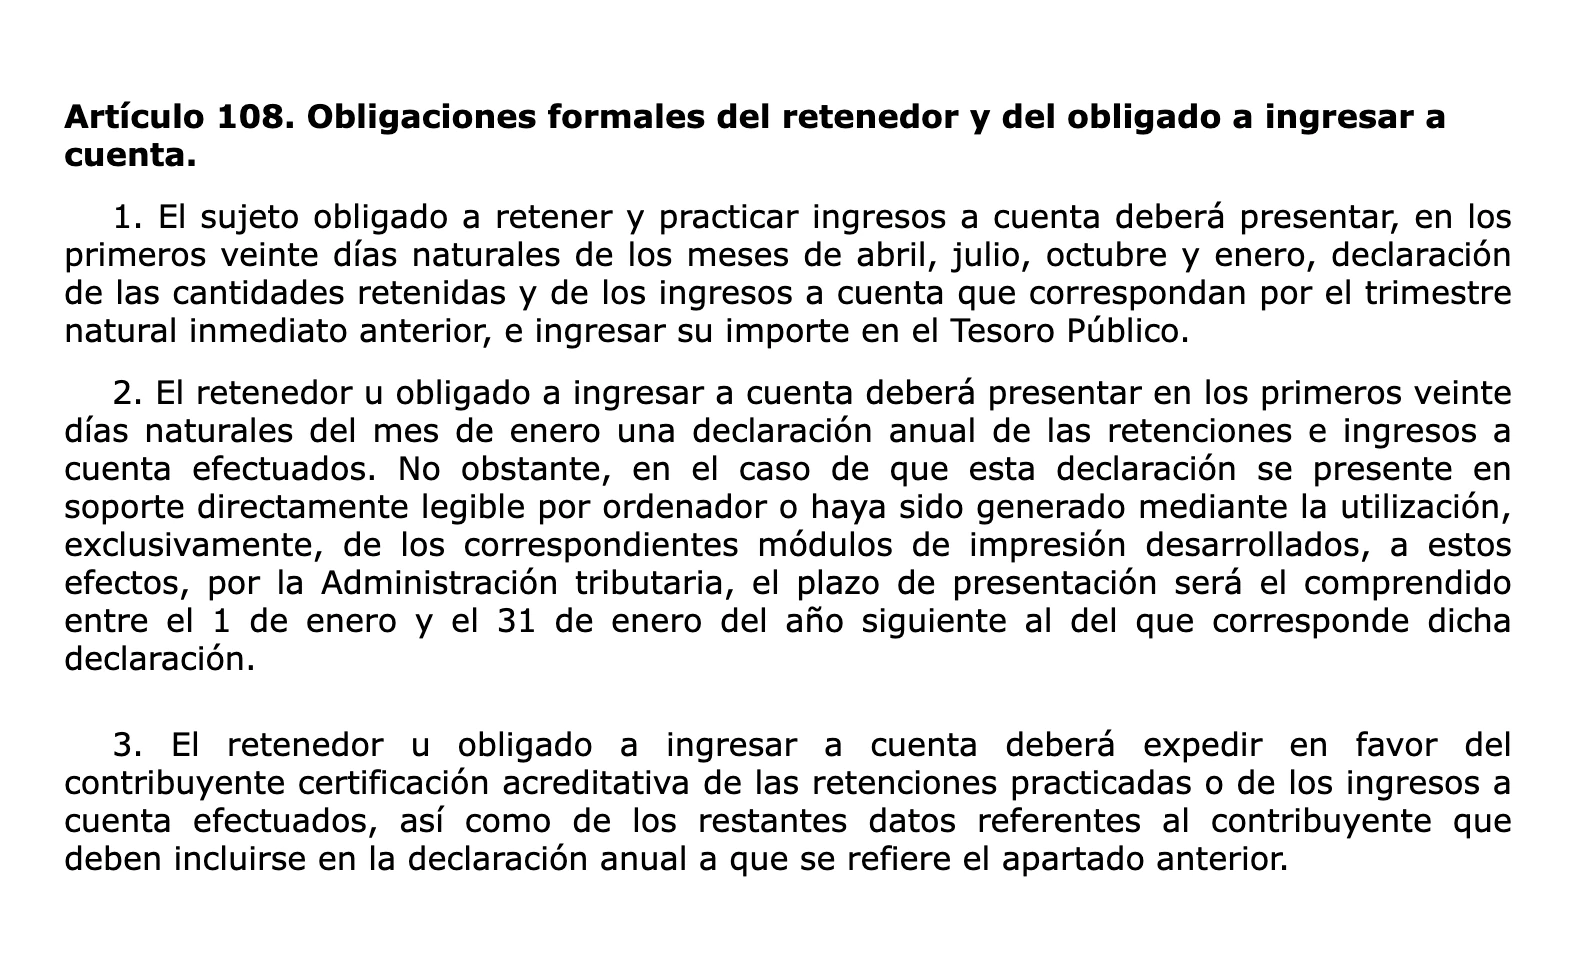
- Modelo 111. In the first 20 calendar days of April, July, October and January you declare and pay what you withheld in the previous quarter (article 108.1). The steps are in the modelo 111 guide.
- Modelo 190. In January you file the year's summary, with each teacher, what you paid them and what you withheld (article 108.2). Filed online, the deadline is 1 to 31 January. The modelo 190 guide explains it.
- The certificate. Each teacher has to have a certificate of their withholding before the income tax return period opens (article 108.3).
If in a quarter you paid nothing subject to withholding, you do not file that quarter's 111 (article 108.1).
Self-employed or an employment contract
The invoice does not decide whether a teacher is self-employed. Employment law applies to anyone working for someone else and within that person's organization and direction (article 1.1 of the Workers' Statute). If a teacher works only for you, with the schedule, room and equipment you decide, it may be an employment relationship even if they send you an invoice. If you have doubts about a specific case, get advice before you start.
With Bookings each teacher has their own column and schedule on the agenda. Your team can see the agenda without ever seeing your invoices or settings.