If you pay salaries or professionals' invoices with IRPF (income tax) withheld, the part you withhold is not yours: you pay it to Hacienda, the Spanish tax agency, every quarter with modelo 111. It is one of the quarterly returns in autónomo taxes in Spain, the guide with the rest of the calendar.
This guide is part of What are tax modelos?, which explains every modelo one by one.
In January you repeat the year person by person in modelo 190. Here we deal with modelo 111: who files it, when, how much is withheld and what happens if you file late.
Who files modelo 111
It is filed by anyone required to withhold who pays income that carries withholding (article 2 of Orden EHA/586/2011, which approves the form). Companies and other entities must file it, including comunidades de bienes (joint ownership businesses). So must autónomos (self-employed people), but only for what they pay as part of their business (article 76.1 of the IRPF Regulation, Real Decreto 439/2007). Modelo 111 mainly covers:
- Salaries of employees and of a company's director.
- Invoices from professionals, such as a lawyer, a designer or a programmer.
- Payments to agricultural, livestock or forestry activities and to certain activities under módulos.
- Prizes from games, competitions or raffles.
Rent for business premises has its own form, modelo 115. If you only receive withholding on your own invoices, you do not file modelo 111: your clients do.
When there is no withholding
You do not withhold from a company for its professional services: they are not among its income subject to withholding (article 60 of the Corporate Tax Regulation). Nor from a shop or a workshop under estimación directa (the standard income method), because among business activities only professional, agricultural, livestock or forestry activities carry withholding, plus some under módulos (article 75.1.c of the IRPF Regulation).
The deadlines
Modelo 111 is filed and paid in the first twenty calendar days of the month after each quarter (article 108.1 of the IRPF Regulation and article 3 of Orden EHA/586/2011):
- First quarter: 1 to 20 April.
- Second quarter: 1 to 20 July.
- Third quarter: 1 to 20 October.
- Fourth quarter: 1 to 20 January of the following year.
If the 20th falls on a Saturday or a non-working day, the deadline moves to the next working day (article 3.1 of the Orden). For example, 20/01/2029 is a Saturday: the fourth-quarter 111 for 2028 can be filed until Monday 22/01/2029. If you pay by direct debit, the window is 1 to 15 of those months (article 3.2). The dates are in the tax calendar.
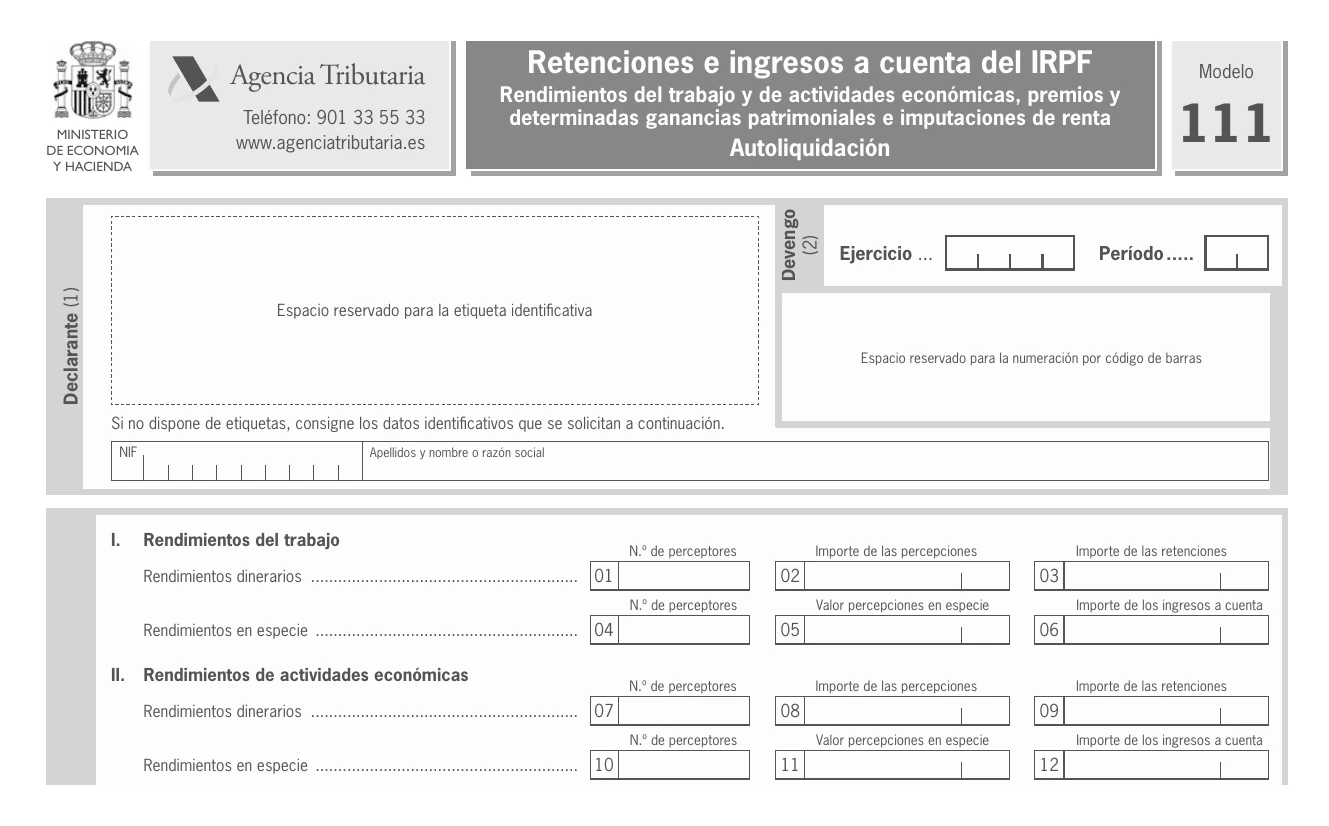
What goes in modelo 111
Modelo 111 carries no names, only the quarter's totals in blocks: employment income, business income and the other types of income. In each block you enter the number of payees, what you paid them and the withholding, with cash payments separate from payments in kind (annex I of Orden EHA/586/2011).
Withholding arises when you pay, not when you receive the invoice (article 78.1 of the IRPF Regulation): a March invoice you pay in April goes into the second-quarter 111. If you forgot to withhold, you still owe the withholding (article 99.4 of the IRPF Law, Ley 35/2006).
How much is withheld
Professionals
The general rate is 15% of the gross income you pay them (article 95.1 of the IRPF Regulation). It is 7% for those starting out: in the year they start their professional activity and the two following years, as long as they carried on no professional activity in the year before the start date. They must notify you of this. You keep that signed notice. Without it you apply 15%.
The same article sets other 7% cases, such as certain artistic activities with low income the year before. Some activities under módulos, such as building work or plumbing, carry 1% (article 95.6). Which rate goes on each invoice is explained in how to choose IVA and IRPF rates.
Employees and directors
Each employee gets their own rate based on what they will earn in the year plus their personal and family situation (article 101.1 of the IRPF Law and article 86 of the Regulation), using the details they give you (article 88). Below certain amounts there is no withholding: for a single person with no children, €15.876 a year (article 81). For contracts shorter than a year the minimum is 2% (article 86.2).
A company director's salary carries 35%, or 19% if the company's turnover in its last closed financial year was under €100.000 (article 80.1.3.º of the Regulation). We cover it in the salary of an SL director.
Quarters with nothing to declare
If you paid no income subject to withholding in a quarter, you do not file modelo 111 for that quarter (article 3.3 of Orden EHA/586/2011). Paying income but withholding nothing because of the amount is different, such as an employee's salary below the threshold. Then you file a nil 111, with nothing to pay.
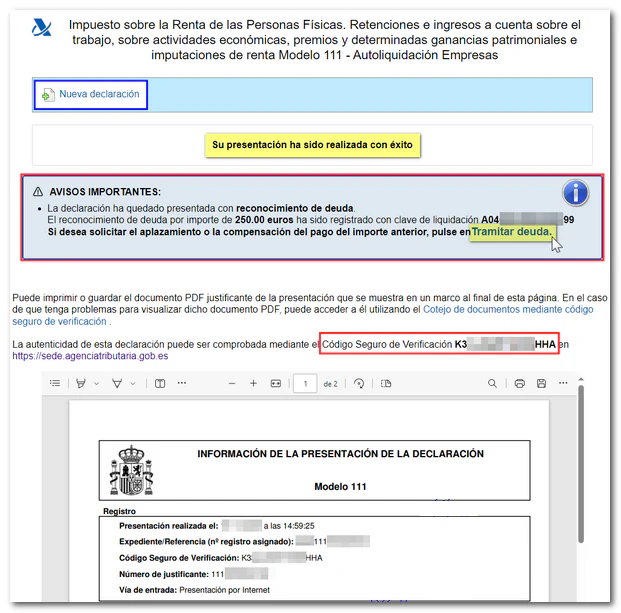
How to file and pay it
Public and private limited companies must file it online with a digital certificate (article 4.1 of Orden EHA/586/2011). As an autónomo you can also use Cl@ve (article 2 of Orden HAP/2194/2013). You can pay by direct debit or through your bank within the deadline.
The Agencia Tributaria site lets you file with an acknowledgement of debt. However, withholding cannot be deferred or paid in instalments: such requests are rejected (article 65.2.b of the Ley General Tributaria, the General Tax Law).
If you file late
If you file modelo 111 late before Hacienda asks you to, there is no penalty: you pay a surcharge of 1% plus another 1% for each full month of delay. After 12 months it is 15% plus late-payment interest (article 27 of the Ley General Tributaria). The surcharge drops by 25% if you pay the tax when you file and pay the surcharge within the period you are given (article 27.5).
An example. You had to pay €900 by 20/04/2026 but you file and pay on 05/06/2026. There is one full month of delay, so the surcharge is 2%: €18. With the reduction, it comes to €13,50.
A nil 111 has no amount to calculate a surcharge on: filing it late is a minor offence with a fixed fine of €200, which drops to €100 if Hacienda has not asked you for it (article 198). If Hacienda asks you first, the surcharge no longer applies and it can fine you. We explain it in surcharges for filing late.
A worked example
You run an online shop. In the second quarter you pay three invoices of €800 before IVA (Spanish VAT) to a designer who started last year and gave you her 7% notice: you withhold €56 from each. You also pay a lawyer an invoice of €1.500 plus €315 of IVA. You withhold 15%, €225, so you pay him €1.590.
In the second-quarter 111, in the business income block, you enter 2 payees, €3.900 of payments and €393 of withholding. You pay €393 by 20/07/2026.
How it links to modelo 190
Modelo 190 repeats the year payee by payee and is filed from 1 to 31 January (article 108.2 of the IRPF Regulation). Its withholding must add up to the same as your four 111s. You also give each payee a certificate before the Renta (annual income tax return) campaign opens (article 108.3).
How Facturaz helps
Facturaz records the withholding on every invoice you receive, so each quarter's modelo 111 and the January modelo 190 come from the same data. On Autónomo Go (€24 + IVA a month) it prepares the official modelo 111 file for you to file yourself with a step-by-step guide. On Autónomo Plus (€44 + IVA a month) our team files it for you. You can try it free for 14 days from pricing.