Every quarter you declare your IVA, the Spanish VAT, with modelo 303: what you charged your clients, what you paid on your expenses and the difference. In January you summarise the year in modelo 390, the annual IVA summary return. It involves no payment: it gathers in one document what you already declared in your four 303s. It is one of the annual returns in autónomo taxes in Spain.
This guide is part of What are tax modelos?, which explains every modelo one by one.
How to fill in each quarter is covered in how to fill in modelo 303. Here we deal with modelo 390: who files it, who is exempt from filing, the deadline, what it carries and how to match it with your 303s.
Who files modelo 390
It is filed by IVA taxpayers who must file periodic returns, in other words anyone who files modelo 303 (article 1.2 of Orden EHA/3111/2009, which approves modelo 390). The duty comes from the IVA Act (article 164.Uno.6.º of Ley 37/1992) and its Regulation (article 71.7 of Real Decreto 1624/1992).
You file it even if you had no IVA charged and deducted nothing in the year (article 71.1 of the Regulation). If you have several activities, there is one return per business owner (article 71.6), so you summarise everything in a single 390.
Who does not file it
- Anyone who only makes exempt supplies. If everything you do is exempt under article 20 of the IVA Act, such as care by a health professional or private lessons in subjects of the education system (article 20.Uno.3.º and 10.º), you file neither modelo 303 nor modelo 390 (articles 71.1 and 71.7 of the Regulation).
- Anyone taxed only under the régimen simplificado or for renting urban property. You are exempt from filing if you file modelo 303 quarterly, are taxed only in the common territory and all your activities are under the IVA régimen simplificado (the flat-rate scheme), are urban property rental or a mix of the two (article 1.3.a of Orden EHA/3111/2009, as worded by Orden HAC/1148/2018). The exemption still applies if you also have activities that require no periodic returns.
- Anyone who keeps their libros registro in the SII. If you keep your libros registro (the IVA record books) on the Agencia Tributaria's electronic site under article 62.6 of the Regulation, you do not file modelo 390 either (article 1.3.b of the Orden).
Two details. If you are exempt, in exchange you fill in a specific section of the last quarter's 303 with your activities, your volume of operations and, if you apply it, your prorrata (article 1.4 of the Orden). The exemption does not apply if you do not have to file the 303 for the last period of the year, for example because you stopped trading earlier: then you file modelo 390 (article 1.3, last paragraph).
The deadline: 1 to 30 January
Modelo 390 is filed in the first thirty calendar days of January of the following year (article 8 of Orden EHA/3111/2009), the same deadline as the fourth-quarter 303 (article 71.4 of the Regulation). The 2026 return is filed in January 2027 on the form approved by Orden HAC/27/2026. The dates are in the tax calendar.
What modelo 390 carries
If you are an autónomo (self-employed) under the general regime, these are the sections of the form you will use (annex IV of Orden HAC/27/2026):
- Statistical data: your activities, from largest to smallest volume, with their IAE heading (the business activity code).
- Operations under the general regime: the IVA charged in the year for each rate with its base, plus the deductible IVA on your expenses and investments.
- Annual result: IVA charged minus deductible IVA for the whole year.
- Results of the returns: the total payable in your 303s for the year and, if the last quarter came out to carry forward or to be refunded, that amount.
- Volume of operations: the total you invoiced in the year, split by type of operation.
If you apply the prorrata, the final percentage for the year is calculated in the fourth-quarter 303, where provisional deductions are adjusted (article 105.Cuatro of the IVA Act). Modelo 390 carries that same percentage in its prorrata section.
A note on rates: in Spain IVA has rates of 21%, 10% and 4%. There is no 0% rate for services. A supply without IVA is either exempt (article 20 of the IVA Act) or not subject, for example because the place-of-supply rules locate it in another country. Each case goes in its own box of the volume of operations.
How to match it with your 303s
Modelo 390 is the sum of your four 303s. If it does not match, the error is almost always in a 303.
An example. You are a designer under the general regime invoicing in Spain at 21%. Over the year you invoice €9.000, €11.000, €8.000 and €12.000 of base per quarter, €40.000 in total, with €8.400 of IVA. Your expenses add up to €6.000 of base with €1.260 of deductible IVA. Your 303s come out payable at €1.575, €2.100, €1.260 and €2.205.
In modelo 390 you show €40.000 of base at 21% with €8.400 of IVA charged, €1.260 of deductible IVA and an annual result of €7.140. In the results section, the total payable for the year is also €7.140: the sum of the four 303s. The volume of operations is €40.000.
What usually throws the figures off:
- An invoice in the wrong quarter. IVA goes in the period in which it becomes chargeable, not when you are paid.
- Credit notes. They reduce the figures of the period in which you issue them. Modelo 390 carries them in its box for adjustments to bases and tax.
- EU transactions. What you buy from European suppliers under the reverse charge counts both in IVA charged and in deductible IVA. What you invoice to EU businesses goes in the volume of operations, without Spanish IVA.
If you find an error in a 303, correct that 303 first (articles 120 and 122 of the Ley General Tributaria, the General Tax Law). Then file modelo 390 with the right figures.
How to file it
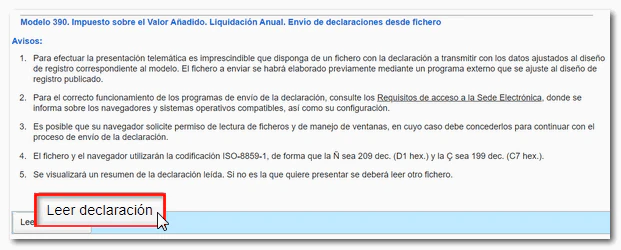
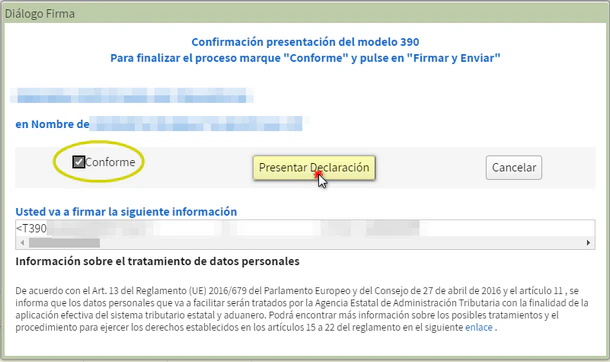
Modelo 390 is filed online on the Agencia Tributaria's electronic site (article 2 of Orden EHA/3111/2009, which refers to Orden HAP/2194/2013). You can fill it in on the site itself or load a file you already have: you choose filing from a file, select it and press Leer declaración. The site shows you its notes before letting you sign. Finally you tick Conforme and press Firmar y Enviar. Keep the receipt.
If you file it late
Because modelo 390 involves no payment, there is no surcharge: the one in article 27 of the Ley General Tributaria is calculated on the amount payable. What applies is a minor offence for not filing on time without financial loss to the Treasury, with a fixed fine of €200 (article 198.1). If you file before Hacienda, the Spanish tax agency, asks you to, the fine is halved to €100 (article 198.2).
How Facturaz helps
In Facturaz modelo 390 is calculated from the same invoices and expenses as your four 303s, so it matches them from the start. If your only activity is renting urban property, it tells you that you are exempt from filing and prepares the section of the last 303. On Autónomo Go (€24 + IVA a month) it prepares the official file of modelo 390 for you to file yourself with a step-by-step guide. On Autónomo Plus (€44 + IVA a month) our team files it for you. You can try it free for 14 days from pricing.