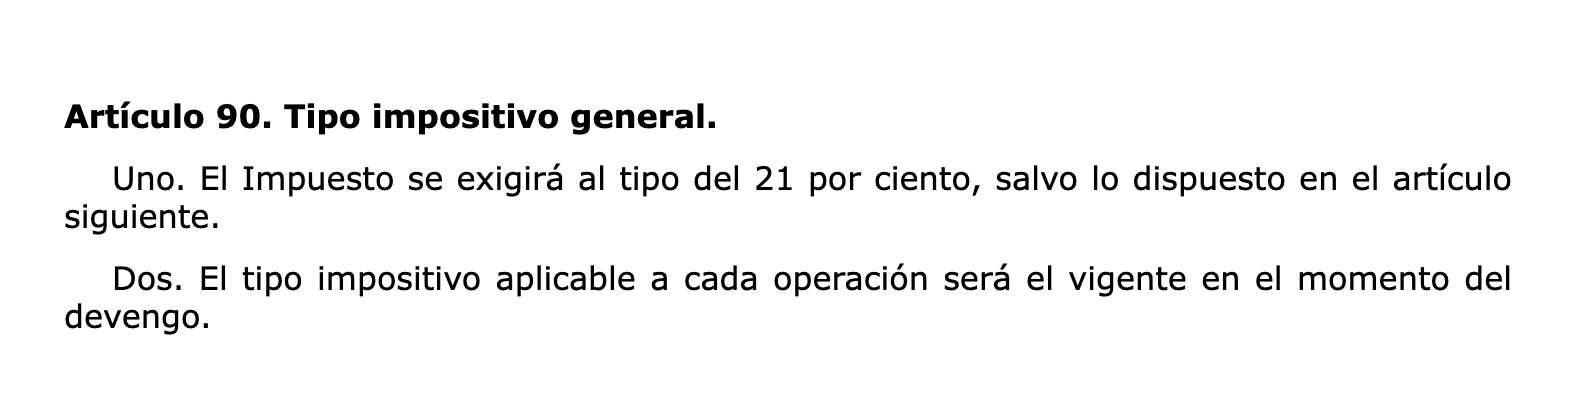
A personal trainer working as an autónomo in Spain charges IVA at 21% on every session they sell, whether single, in a pack or with a monthly membership. It is the tax's standard rate (article 90 of Ley 37/1992). No exemption or reduced rate reaches a self-employed trainer. If you charge €40 a session with IVA included, €6,94 of it belongs to Hacienda.
Here is why, how to work it out and what goes on the invoice, with the article behind each rule. If you also want clients to book themselves and every payment to come with its invoice, see Bookings for personal trainers.
The IVA rate on a training session
The IVA Law sets a standard rate of 21% for everything without a reduced rate (article 90.Uno). The reduced rates are a closed list, article 91. Sport appears on it only once: amateur sports shows, at 10%. Watching a match is not training, so your sessions go at 21%.
It makes no difference where you train the client: at their home, in a park, in a room you rent or by video call. Nor how you charge. A single session, a pack of ten and a monthly membership all carry the same 21%.
Why the sport exemption does not reach you
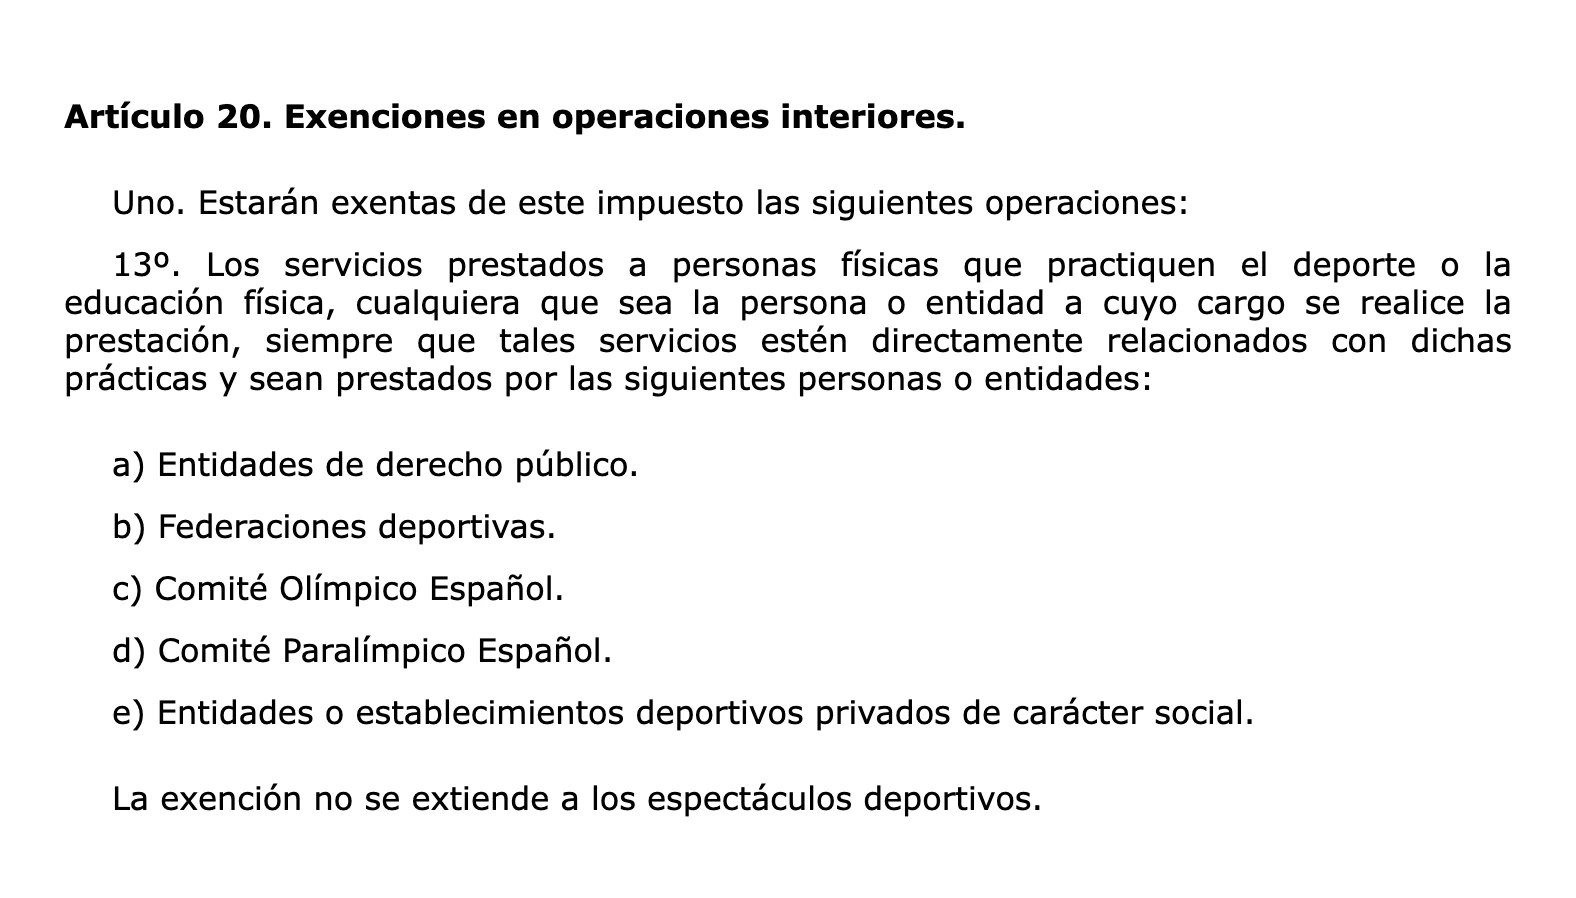
The law exempts services to people who practice sport or physical education (article 20.Uno.13.º). But only when one of these provides them:
- Public bodies, such as a municipal sports center.
- Sports federations.
- The Spanish Olympic Committee and the Spanish Paralympic Committee.
- Private sports entities of a social nature, that is, nonprofits.
An autónomo is none of them. Nor is a gym run for profit. That is why a nonprofit club's fee can carry no IVA while your session does.
Nor the teaching exemption
Two other exemptions are sometimes quoted. Neither covers training:
- Teaching. Article 20.Uno.9.º exempts teaching by public or authorized centers, but expressly leaves out services related to the practice of sport provided by businesses other than schools.
- Private lessons. Article 20.Uno.10.º exempts private lessons on subjects in the curricula of the education system. A personal training plan is not a lesson on a subject of those curricula.
How much it is: the price with IVA inside
A private client gets the total price, all taxes included (article 60.2.c of Real Decreto Legislativo 1/2007, the consumer law). If you advertise €40 a session, the client pays €40 and the IVA and your share are both inside it:
| What you charge | Base | IVA at 21% |
|---|---|---|
| Single session of €40 | €33,06 | €6,94 |
| Pack of 10 sessions for €350 | €289,26 | €60,74 |
| Monthly membership of €120 | €99,17 | €20,83 |
The base is what you charge divided by 1,21. The IVA is the difference. If you want your share to be a round €40, the client's price becomes €48,40.
An invoice for every payment
Every session, pack and membership gets an invoice (article 2.1 of Real Decreto 1619/2012). If the client pays in advance, as with a pack, the invoice is for that payment, on the day you are paid. We cover it in detail in session packs for personal trainers.
For payments up to €400 with IVA included a simplified invoice is enough (article 4.1.a). Above that, or when the client is a business, it is a full invoice with their name and tax ID (NIF).
Income tax withholding: only when a business pays you
A private client never withholds income tax (IRPF) from you. Withholding is a duty of the businesses, autónomos and organizations that pay you as part of their own activity (article 76 of Real Decreto 439/2007, the IRPF Regulation). If you teach for a gym, a hotel or a company and invoice them, the invoice may carry withholding. We explain it in teaching for a studio, a gym or a hotel.
What you do with the IVA you collect
The IVA on your invoices is not yours. Every quarter you declare it on modelo 303 and subtract the IVA on what you buy for work: equipment, the room you rent, the phone you take bookings on. The difference is what you pay. The steps are in the modelo 303 guide.