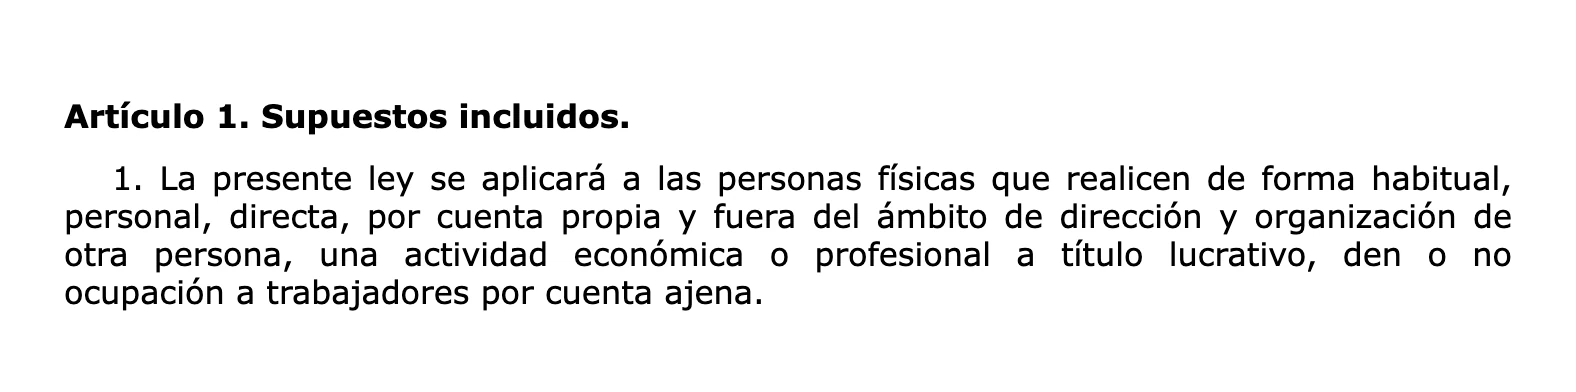
If you train clients on your own account on a regular basis, you are an autónomo, self-employed. That is how the law puts it: someone who carries out an economic activity regularly, personally, directly and on their own account (article 1.1 of Ley 20/2007, the Self-Employed Workers' Statute). It makes no difference whether you train at the client's home, in a park or in a room you rent.
Being self-employed means two registrations before the first session, an invoice for every payment and two forms every quarter. Here is each step. And if you want your bookings, packs and their invoices in one place, see Bookings for personal trainers.
The two registrations, before you start
- With Hacienda, on modelo 036. It is filed before the activity starts (article 9 of Real Decreto 1065/2007). On it you choose your activity code and how you will be taxed. We go through it step by step in the modelo 036 guide.
- With the Seguridad Social. You register as self-employed and pay a monthly contribution. If it is your first registration, or you have not been registered in the previous two years, you can ask for a reduced contribution for the first twelve months (article 38 ter of Ley 20/2007). If you already had the reduced contribution in your previous registration, you need three years without being registered (article 38 ter.4). Its amount is set each year by the budget law. We cover it in the tarifa plana guide.
The reduced contribution is requested at the moment you register (article 38 ter.3), so tick it on the same application.
A personal trainer's activity code
Your activity code (epígrafe) tells Hacienda what you do. For a self-employed trainer there are two options, both professional activities:
- Group 826 of section two: teachers of various subjects, physical education and sport among them. It fits if what you do is teach and lead training.
- Grouping 04 of section three: sport professionals. Its group 049 covers sport professionals with no code of their own.
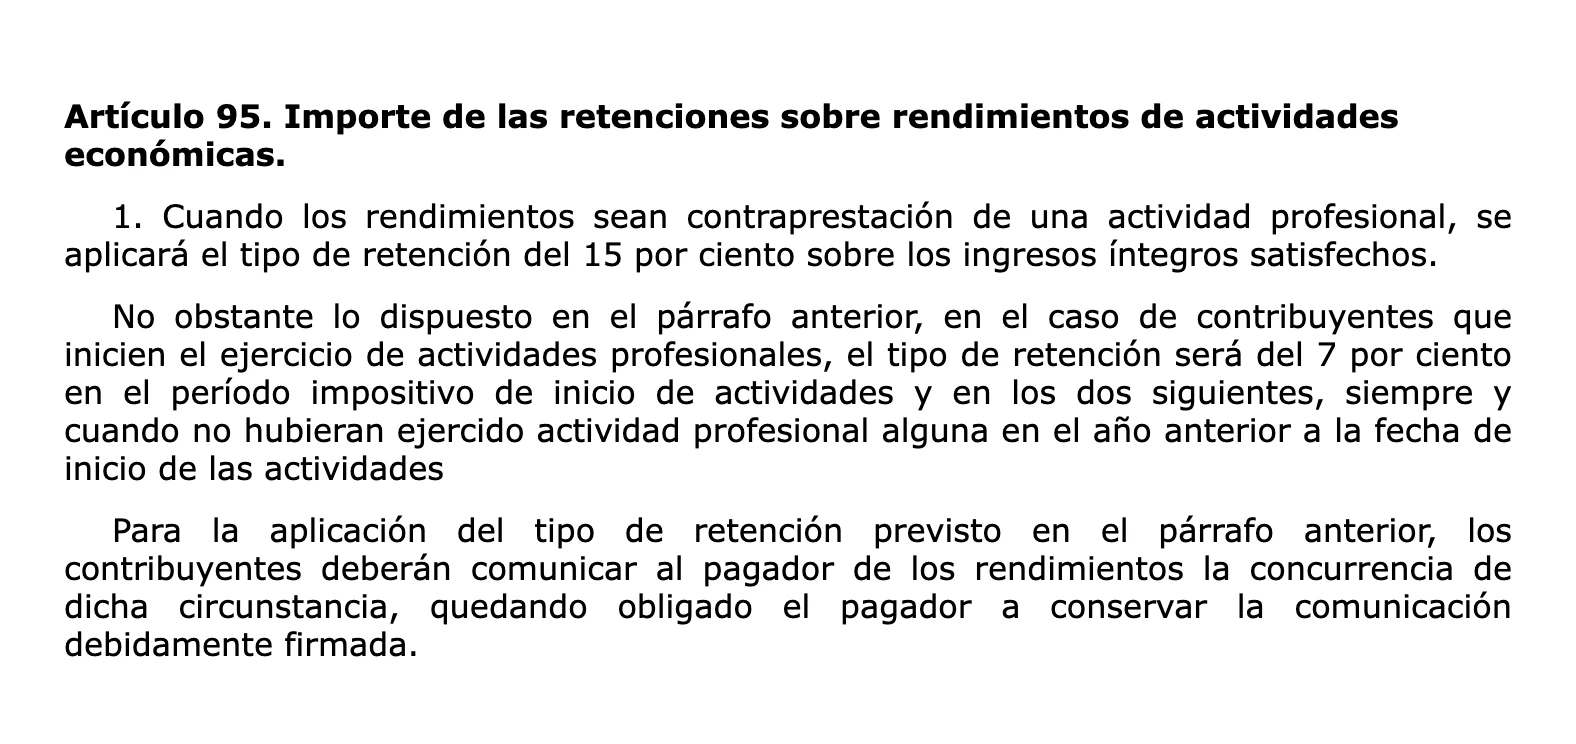
Being a professional activity matters when you invoice a business, such as a gym or a hotel: that business withholds 15% income tax (IRPF), or 7% in the year you start and the two after if you had no professional activity the year before (article 95.1 of the IRPF Regulation). You tell them about the 7% in writing. If you open your own center, the code is a different one. There is more in how to choose your activity code.
An invoice from the first session
Every session, pack or membership you are paid for gets an invoice (article 2.1 of Real Decreto 1619/2012), with 21% IVA. Spain's tax directorate (Dirección General de Tributos) confirmed it for a self-employed trainer in ruling V0759-26 of 6 April 2026. Why there is no exemption is in IVA for personal trainers.
If you sell packs, the IVA goes on the day you are paid. We cover it in session packs for personal trainers.
The forms every quarter
| Modelo | What you declare | When |
|---|---|---|
| 303 | The IVA you charge minus the IVA on what you buy for work | 1 to 20 April, July and October; for the fourth quarter, 1 to 30 January |
| 130 | 20% of your profit for the year to that quarter, toward your income tax | The same dates |
| 100 | The year's income tax return (Renta), counting what you paid on the 130s | April to June of the following year |
Modelo 130 is not filed if in the previous year at least 70% of your professional income had withholding (article 109.2 of the IRPF Regulation). A trainer paid mostly by private clients does not reach that 70%, so as a rule you file it. The steps are in the modelo 303 and modelo 130 guides.
If you also work for a gym
Many trainers have a contract at a gym and their own clients in the evenings. That is allowed: you are registered as an employee and as self-employed at the same time, which is called pluriactividad. We explain it in pluriactividad.
If you would rather not do the registrations yourself, our team handles your autónomo registration with Hacienda and the Seguridad Social, with the category for your work chosen with you.