Dietas (allowances) is the word used for what a company pays its employees when they travel. For an autónomo the law does not talk about dietas but about your own meal costs (gastos de manutención), your travel and client hospitality (atenciones a clientes), each with its own rule. This article expands the meals and travel section of how to deduct expenses as an autónomo, the guide that covers every deductible expense.
Here you have the conditions to deduct your meals, the daily limits, how trips and hotels are treated, what happens when you invite a client and when you can recover the IVA (Spanish VAT) on the bill. Each rule cites the article it comes from.
The four conditions to deduct your meals
Since 01/01/2018, the IRPF (personal income tax) Law treats as deductible in estimación directa (direct assessment) the autónomo's own meal costs that meet four conditions (article 30.2.5.ª.c of Ley 35/2006, as worded by Ley 6/2017):
- You incur them while carrying out your business. There has to be a link with your work. The Dirección General de Tributos (DGT, the tax policy directorate) states that eating on a working day is not enough by itself (binding ruling V1184-22 of 26/05/2022).
- In a restaurant or hospitality venue. A restaurant, a bar or a café. Supermarket shopping does not count.
- You pay electronically. Card, mobile payment or bank transfer. What you pay in cash is not deductible.
- Within the daily limits that the IRPF Regulation sets for employees' allowances.
You do not have to eat in another municipality. The law's reference to the Regulation is limited to the amounts, so the requirement to travel to a different municipality, which does apply to employees, does not apply to autónomos (binding rulings V3619-20 of 22/12/2020 and V0124-21 of 28/01/2021).
The daily limits
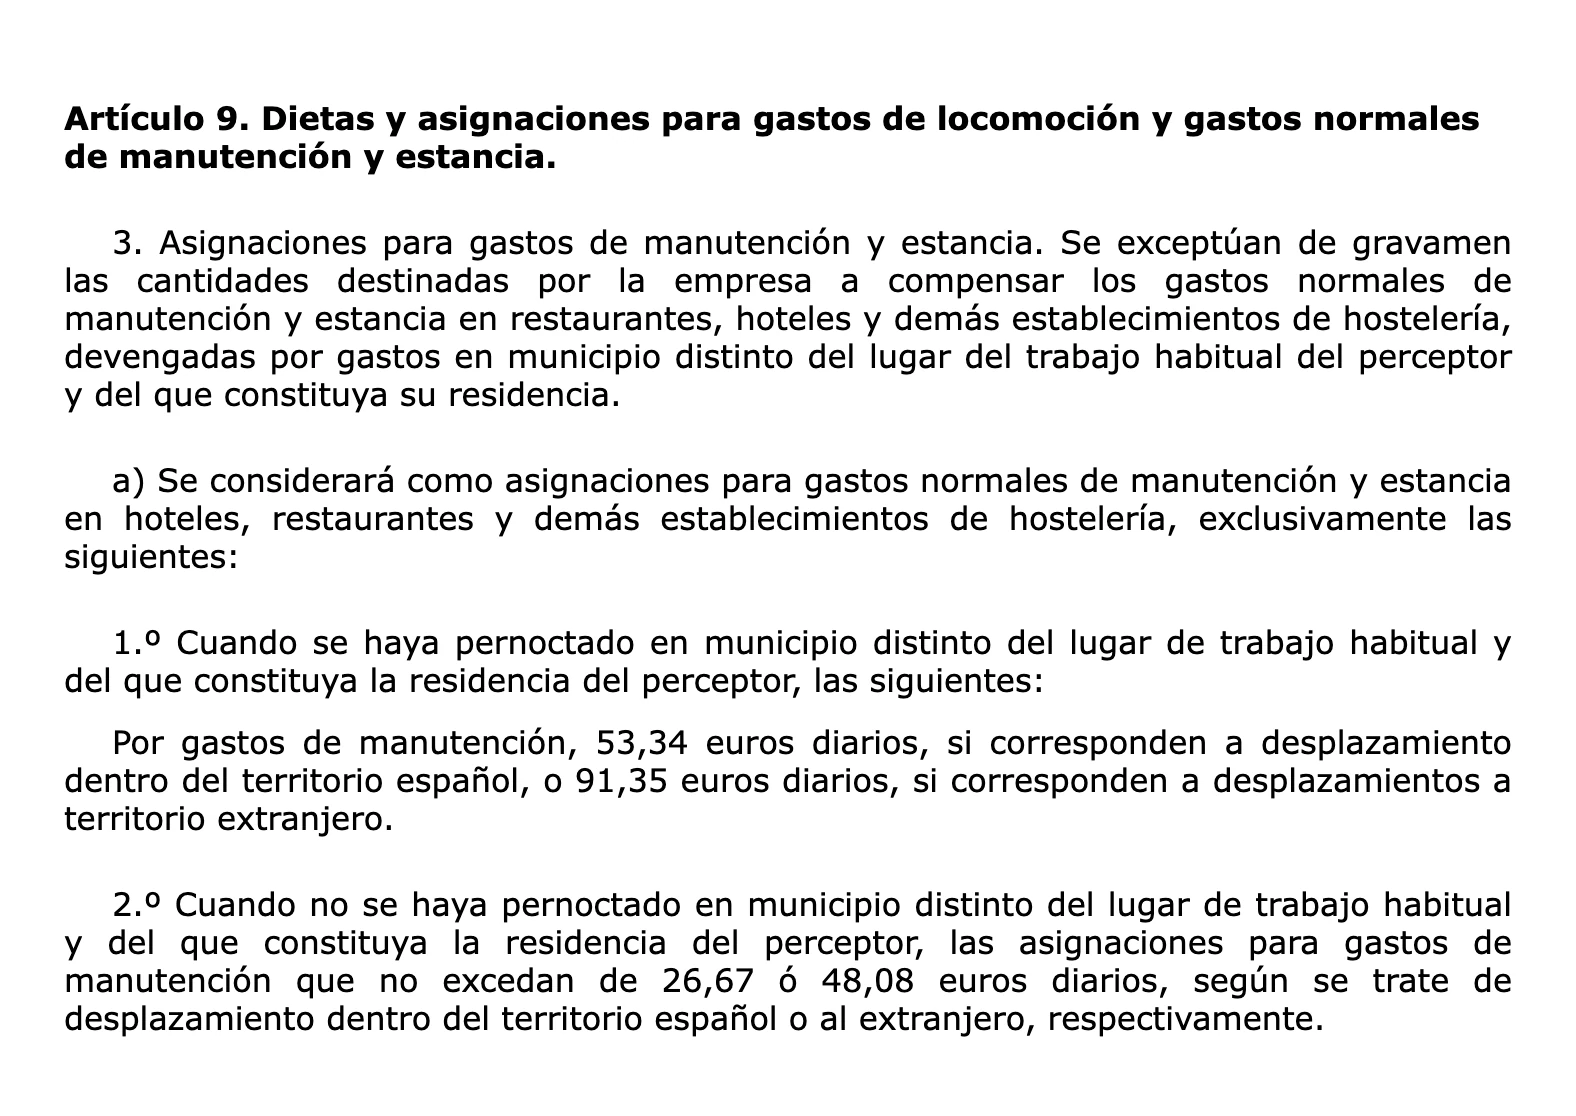
The limits are those in article 9.A.3 of the IRPF Regulation (Real Decreto 439/2007):
| Situation | In Spain | Abroad |
|---|---|---|
| No overnight stay | €26,67 | €48,08 |
| Overnight stay | €53,34 | €91,35 |
They are limits per day, not per meal. An example: Daniel is a photographer, does a shoot in Spain and goes home to sleep. He pays €18 for lunch and €15 for dinner by card. He spends €33 but only deducts €26,67. If he stayed away overnight for the job that day, the limit would be €53,34 and he could deduct the full €33.
Trips and hotels: business expenses
Train, plane, bus or taxi tickets and the hotel for a work trip have no special rule. They are business expenses under the general rules: a link with your income, proof and allocation to the right year (article 28.1 of the IRPF Law). The Regulation's limits only cover meals: the DGT states that the reference to article 9 does not extend to accommodation (binding ruling V0117-21 of 28/01/2021). The hotel has no daily cap: it counts if the trip is for work and you have the invoice.
If you drive your own car, you only deduct its costs if the car is assigned to the business. Nor can you apply a per-kilometre amount: the same ruling V0117-21 rejects using the employees' mileage rules for a professional. We explain it in car expenses for autónomos.
Client meals: client hospitality
Taking a client or a supplier out for a meal is not your own meal cost: it is client hospitality. IRPF calculates your profit with the Corporate Tax rules (article 28.1 of the IRPF Law). That law accepts client or supplier hospitality expenses up to 1% of your net turnover for the year (article 15.e of Ley 27/2014). The DGT applies this rule to an autónomo's client meals (binding ruling V0849-21 of 12/04/2021).
With turnover of €40.000, you can deduct up to €400 a year in client meals and gifts. Note who you ate with and why: you have to be able to prove the link with your business.
IVA on meals, hotels and travel
The IVA Law does not allow deducting IVA on travel, hospitality and restaurant services, unless their amount is a deductible expense for IRPF or Corporate Tax (article 96.Uno.6.º of Ley 37/1992). If your meal is deductible for IRPF, you can deduct its IVA. If you paid it in cash, it is not deductible for IRPF and neither is its IVA. IVA on client hospitality is never deductible, even when the expense counts for IRPF (article 96.Uno.5.º).
You also need an invoice with your details (article 97 of the IVA Law). Restaurants and bars can give you a simplified invoice of up to €3.000 (article 4.2.e of Real Decreto 1619/2012). For it to work, ask them to add your NIF (tax ID), your address and the IVA amount separately, as article 7.2 of the same regulation provides. A till receipt without those details does not let you deduct the IVA. It is explained in the simplified invoice. You subtract that IVA in your modelo 303.
Common mistakes
- Paying in cash. The meal stops being deductible for IRPF and its IVA goes with it.
- Keeping only the till receipt. Without your NIF on the invoice you do not recover the IVA.
- Adding meals from days you do not work. No link with the business means no expense.
- Treating a client meal as your own meal. It is client hospitality: it goes to the 1% limit and its IVA is not deductible.
- Applying the employees' mileage rate. The €0,26 per kilometre is for what a company pays its staff.
How Facturaz handles it
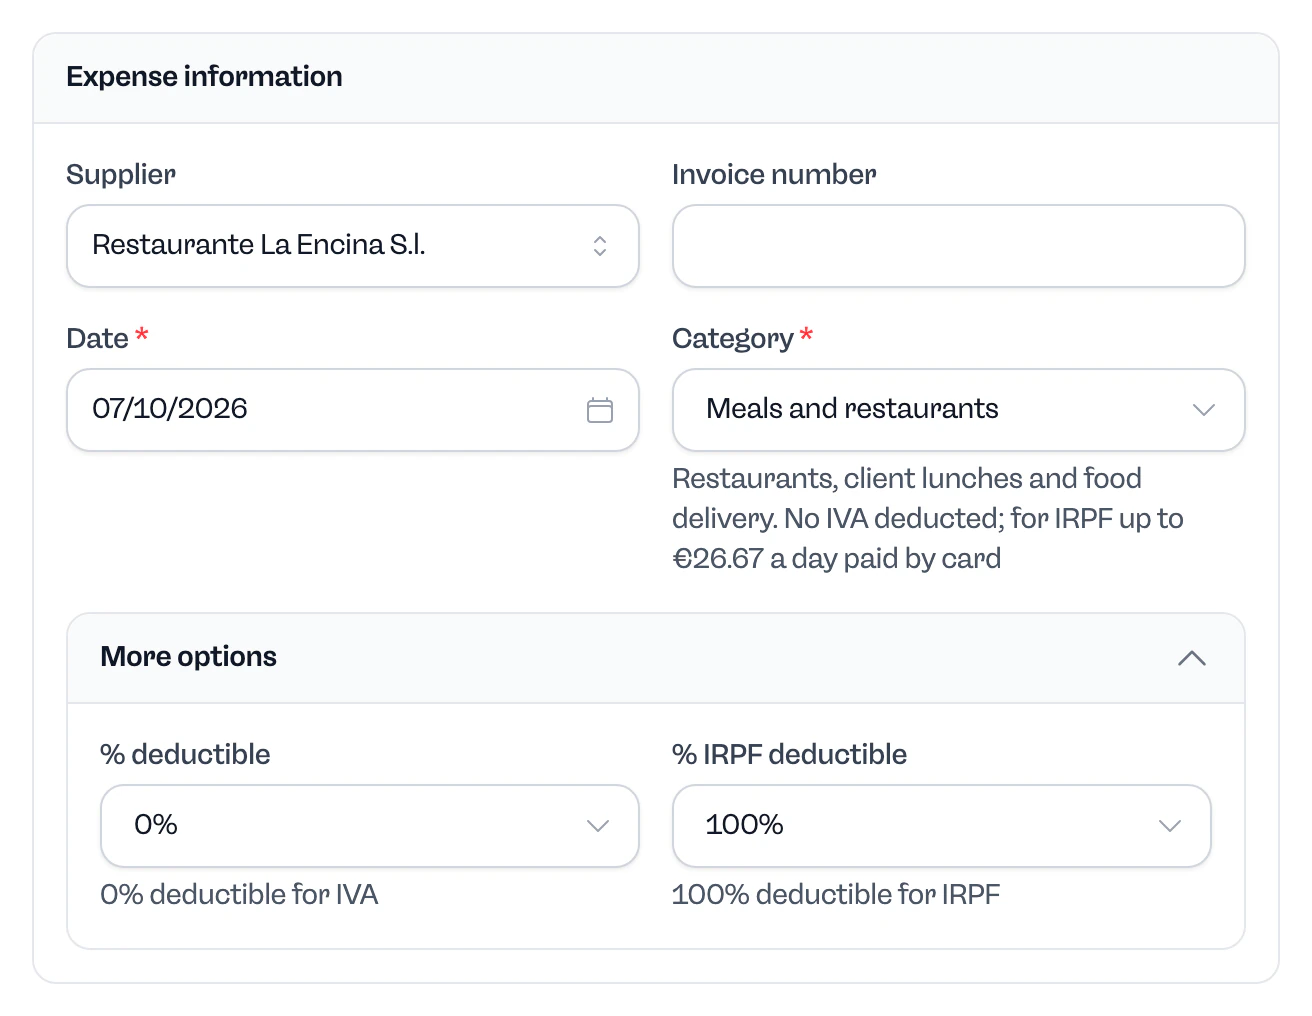
In Facturaz you take a photo of the receipt and the AI fills in the supplier, date, base, IVA, total and category. Meals are capped at €26,67 a day for you, a meal paid in cash deducts nothing for IRPF and a till receipt without your NIF deducts no IVA. Autónomo Go costs €24 + IVA a month and Autónomo Plus €44 + IVA a month, with 14 days free, on Facturaz pricing.