Almost every autónomo (self-employed person in Spain) uses their mobile for work and almost every one also uses it in their private life. That is the problem: neither IRPF (personal income tax) nor IVA (Spanish VAT) lets you split a mobile between work and private life the way you split your home electricity. This article expands on how to deduct expenses as an autónomo, the guide that covers every deductible expense and its conditions.
Here are the line, the handset, the IVA on each and why your mobile is not part of the 30% home rule, with the article or ruling behind each rule.
The line: deductible only if used exclusively for work
The monthly line fee is a running expense. The Dirección General de Tributos (DGT, the tax policy directorate) answers that for IRPF it is deductible to the extent the line is used exclusively for the business. If you use it both for work and in your private life, you cannot deduct any of it (binding ruling V2554-23 of 25/09/2023, which cites V0601-14, V2382-13 and V2400-13). It repeats this in ruling V1233-25 of 04/07/2025.
You prove the exclusive use, by any means admitted in law (article 106 of the Ley General Tributaria, the General Tax Law, cited in V1233-25). A work-only line, with the number you give your clients, is the simple way to prove it. If your bill covers several lines, only the work line counts.
IVA on the line
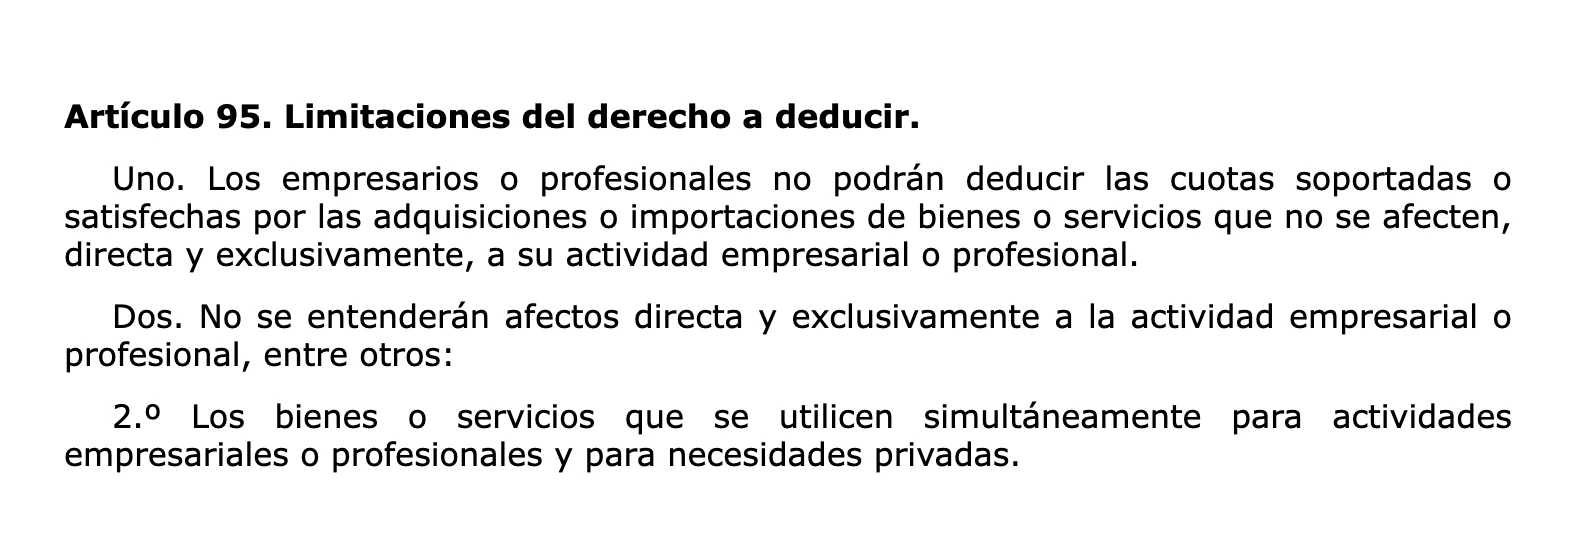
The IVA Law does not allow deducting the IVA on goods or services used both for the business and for private needs (article 95.Uno and Dos.2.º of Ley 37/1992). With a mixed-use line you recover none of the IVA. With a work-only line you deduct all of its IVA in your modelo 303.
The TEAC (the central tax appeals tribunal) accepted in its ruling of 19/07/2023 deducting, in proportion to use, the IVA on utilities of a property partly used for the business. The DGT clarifies that this position does not reach mobile phone services, because they are not a utility of a property (ruling V2554-23).
The handset: it is depreciated
The handset is an asset you use for more than a year, so it is not deducted in full the day you buy it: it is spread through depreciation. The DGT says so for the handset of a work-only line (ruling V1233-25).
To deduct it, the handset has to be assigned to your business. The IRPF Regulation does not treat as assigned an asset you use both for the business and for private needs, unless the private use is incidental and clearly irrelevant (article 22.2.1.º of Real Decreto 439/2007). That irrelevant use means using a business asset for yourself on days or at hours when you are not working (article 22.4). Unlike a car, a mobile is not among the assets for which that tolerance does not apply.
What you cannot do is deduct a percentage of the handset. Indivisible assets cannot be partly assigned (article 29.2 of Ley 35/2006, the IRPF Law; article 22.3 of the Regulation). A mobile cannot be divided. Also record it in your capital assets register (libro registro de bienes de inversión): an asset you own that is not in your records is presumed not to be assigned unless you prove otherwise (article 22.2.2.º of the Regulation).
How much you depreciate each year
Under estimación directa normal, if the handset is new and costs no more than €300, you can deduct it in full in the year you buy it. IRPF calculates your business income with the Corporate Tax rules (article 28.1 of the IRPF Law). That law allows free depreciation of new tangible fixed assets with a unit value of no more than €300, up to €25.000 a year (article 12.3.e of Ley 27/2014). Under estimación directa simplificada, the IRPF Regulation says to depreciate with its simplified table (article 30.1.ª) and does not mention this free depreciation, so check before you apply it.
Above €300, you spread it over several years. The depreciation tables do not name mobiles and the DGT speaks of the rate that applies. Treated as IT equipment, the maximum is 25% a year in the table in article 12.1.a of Ley 27/2014 (information processing equipment) and 26% in the simplified table of the Orden of 27 March 1998 (information handling equipment). A €900 handset at 25% gives €225 a year for four years. The year-by-year calculation is in capital assets and depreciation.
IVA on the handset
For IVA the same rule as for the line applies: if you use the handset for the business and for yourself, its IVA is not deductible (article 95.Dos.2.º of the IVA Law). Deducting in proportion to use is only allowed for capital goods (article 95.Tres.1.ª). The law does not treat as a capital good one worth less than €3.005,06 (article 108.Dos.5.º, which sets 500.000 pesetas). A €900 mobile is not one. If it is only for work, you deduct all its IVA. If it is mixed, none.
The 50% presumption you know from cars does not work here either. It is only for passenger cars, their trailers, mopeds and motorcycles (article 95.Tres.2.ª). We explain it in car expenses for autónomos.
| Case | IRPF | IVA |
|---|---|---|
| Work-only line | Fully deductible | Fully deductible |
| Mixed-use line | Nothing | Nothing |
| Work-only handset | Depreciation; under directa normal, in full if new and no more than €300 | Fully deductible |
| Mixed-use handset under €3.005,06 | Nothing, unless private use is only outside working hours | Nothing |
Why your mobile is not part of the 30% home rule
The 30% rule lets you deduct the utilities of your main home when part of it is used for the business, such as water, gas, electricity, telephone and internet (article 30.2.5.ª.b of the IRPF Law). The DGT applies it to the home landline and internet. It does not apply it to a mobile line, because that is not a utility linked to a home (ruling V2554-23). Home fibre does follow that rule: it is in home utilities for autónomos.
The invoice, in your name
To deduct IVA you need the invoice (article 97.Uno of the IVA Law) showing your name and NIF (tax ID) as the customer (article 6.1 of Real Decreto 1619/2012). If the line is in your partner's name, the invoice is not yours. For IRPF, expenses are justified primarily with the invoice (article 106.4 of the General Tax Law). Put the work line contract in your name and ask for a full invoice when you buy the handset.
How Facturaz handles it
In Facturaz you take a photo of the bill and the AI fills in the supplier, date, base, IVA, total and category. Mobile bills go to the Telephony category, separate from home utilities, so the 30% does not apply to them. Each expense has its own deductible percentage for IVA and for IRPF: if your line is mixed-use, set both to 0. Autónomo Go costs €24 + IVA a month and Autónomo Plus €44 + IVA a month, with 14 days free, on Facturaz pricing.