If you work from home, part of your electricity, water, gas, phone and internet is a business expense. The law sets how much. It is not whatever share seems fair to you. This article is part of how to deduct expenses as an autónomo, the guide that covers every deductible expense and its conditions.
Here you have the IRPF (personal income tax) formula for utilities, what happens with rent, IBI (the local property tax), community fees and the mortgage, the current position on the IVA (Spanish VAT) on those bills and why they have to be in your name. Each rule cites the article of the law or the ruling it comes from.
The 30% rule for power, water, gas, phone and internet
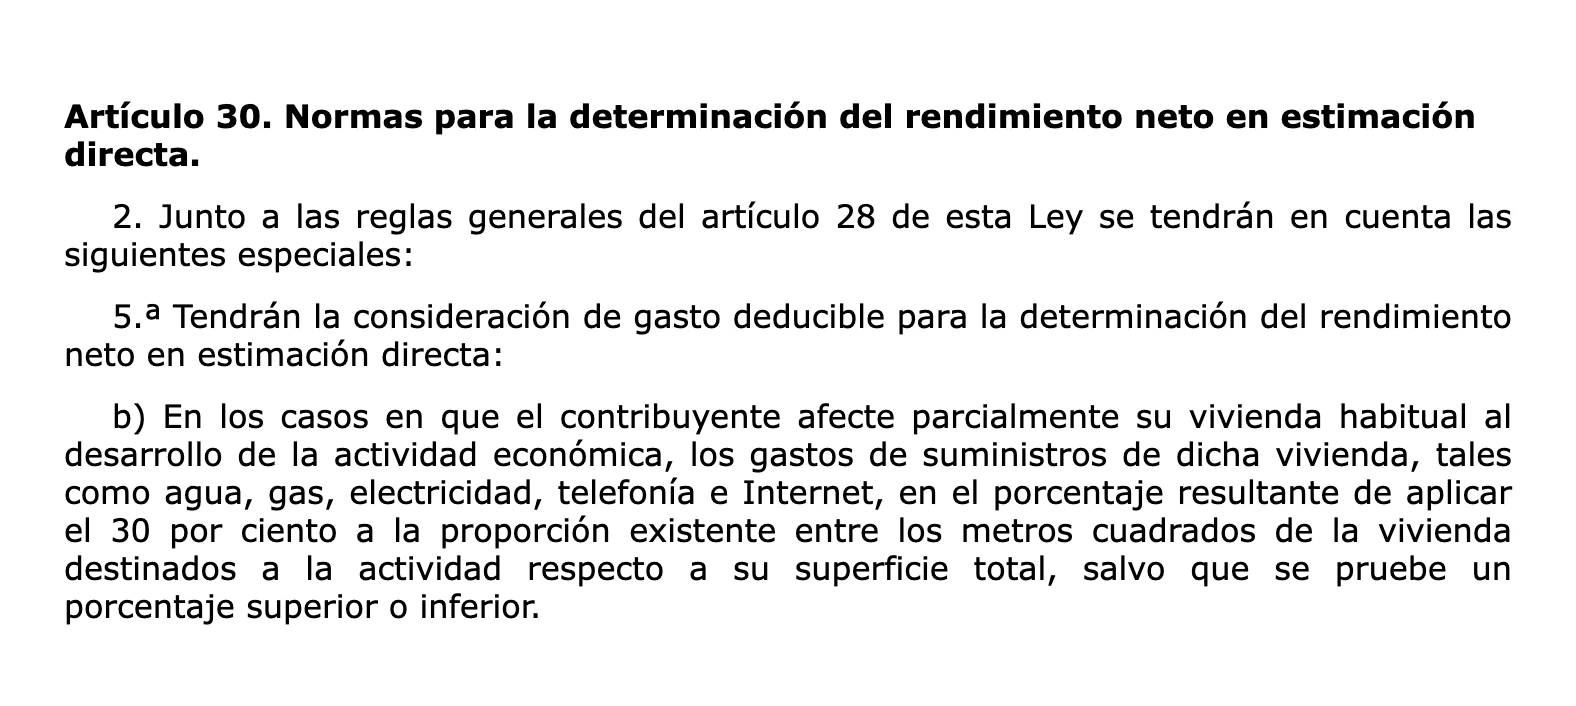
When you use part of your main home for your business, the home's utilities are deductible at the percentage that results from applying 30% to the ratio between the square metres you use for the business and the total floor area of the home, unless you prove a higher or lower percentage (article 30.2.5.ª.b of Ley 35/2006, the IRPF Law). The law lists water, gas, electricity, telephone and internet as examples.
An example. Lucía is a translator and works in a 12 m² room of an 80 m² flat. The room is 15% of the home. 30% of that 15% is 4,5%, the percentage she applies to each utility bill:
| Utility | Amount per year | Deductible (4,5%) |
|---|---|---|
| Electricity | €840 | €37,80 |
| Gas | €360 | €16,20 |
| Water | €300 | €13,50 |
| Internet and landline | €480 | €21,60 |
| Total | €1.980 | €89,10 |
The figure is small because the law assumes most of a home's consumption is private. If you can prove another percentage, for example with a separate meter for the office, you can apply it. The proof is yours to give: whoever claims a right has to prove the facts it rests on (article 105.1 of the Ley General Tributaria, the General Tax Law).
Which part of the home counts as an office
The 30% rule assumes you have assigned part of your home to the business (afectación parcial). The IRPF Regulation only allows assigning parts of an asset that can be used separately and independently from the rest (article 22.3 of Real Decreto 439/2007). The Dirección General de Tributos (DGT, the tax policy directorate) applies this to homes: when that condition is met, you can assign the part you use for work (binding ruling V0229-20 of 04/02/2020).
- A room you use only for work fits the rule. A table in the living room your family also uses is hard to defend as a separate part.
- It has to be your main home. That is the home the 30% rule names. A second home is outside it.
- Declare where you work. The tax census records the premises where you carry out your business, with their address and cadastral reference (article 5.b.12.º of Real Decreto 1065/2007). If you work at home, that place is your home. You report it in modelo 036.
- Keep your measurements. A floor plan or the land registry extract with the total area, together with the room's measurements, help you explain your percentage in a tax review.
Your mobile is not part of the home rule
The 30% rule covers the home's utilities. For a mobile line you use both for work and in your private life, the DGT answers that you cannot deduct any of the cost for IRPF or its IVA. If the line is only for work, it is fully deductible (binding ruling V2554-23 of 25/09/2023). A work-only line is the simple way to solve it.
If you own the home: IBI, community fees, mortgage and depreciation
Assigning part of your home also lets you deduct, in proportion to that part, the costs of owning it. Ruling V0229-20 lists depreciation (excluding the land), IBI, interest, the waste collection charge, community fees and the home's liability insurance. The 30% does not apply here: the full proportion does. With Lucía's office, an IBI bill of €600 gives €90 deductible.
Depreciation is calculated on the purchase price of the home without the land, for the assigned part, from the moment you start using it for the business. In estimación directa simplificada (the simplified direct assessment method), the table in the Orden of 27 March 1998 sets a maximum rate of 3% and a maximum period of 68 years for buildings and other constructions (article 30.1.ª of the IRPF Regulation). In the normal method, the table in article 12.1.a of Ley 27/2014, the Corporate Tax Law, gives homes 2% and 100 years. If the building cost you €150.000, the 15% share is €22.500. Under the simplified method you can depreciate up to €675 a year.
Record that part in your capital assets register (libro registro de bienes de inversión). An asset you own that is not in your records is presumed not to be assigned to the business unless you prove otherwise (article 22.2 of the IRPF Regulation). How a purchase is spread over the years is explained in capital assets and depreciation.
If you rent your home
If the home is rented, the matching share of the rent is a business expense. Binding ruling V1153-26 of 20/05/2026 accepts it in proportion to the part of the home assigned to the business, with the same condition that it is a separate part. Utilities follow the 30% rule. With Lucía's office and rent of €900 a month, she deducts €135 a month, €1.620 a year.
Renting a home is exempt from IVA (article 20.Uno.23.º.b of Ley 37/1992, the IVA Law), so there is no IVA to recover on the rent.
IVA on utilities: the TEAC position
The IVA Law only allows deducting IVA on what is used directly and exclusively for the business. It specifically excludes goods and services used both for the business and for private needs (article 95.Uno and Dos.2.º of Ley 37/1992). With that wording, the DGT used to refuse the IVA on electricity or water in a home that is also an office.
The Tribunal Económico-Administrativo Central (TEAC, the central tax appeals tribunal) changed that position in its ruling of 19/07/2023 (RG 00/06654/2022), issued to unify doctrine. It reads article 95.Cuatro of the IVA Law in light of articles 168 and 168 bis of Directive 2006/112/EC and allows deducting the IVA on water, electricity and gas supplied to a property that is part of the business assets and is used both for the business and privately, in proportion to its business use. The DGT applied that change to the internet of a partly assigned home in ruling V2554-23. You subtract that IVA in your modelo 303.
- The 30% is an IRPF rule. The IVA Law does not contain it. The TEAC speaks of the proportion of use without saying how to measure it, so you have to be able to justify the percentage you apply.
- You prove the business use. Ruling V2554-23 notes that it is a question of fact and that the proof has to be available when you deduct.
- A shared mobile is still out. The change covers utilities of a partly assigned property, not a mixed-use mobile line.
The invoice, in your name
To deduct IVA you need the invoice (article 97.Uno of the IVA Law), showing your name and your NIF (tax ID) as the customer (article 6.1 of Real Decreto 1619/2012). If the electricity contract is in your partner's or your landlord's name, the invoice is not yours and you do not deduct its IVA. For IRPF, expenses are justified primarily with the invoice (article 106.4 of the General Tax Law). If you are going to deduct utilities, put the contracts in your name. If you also use your car for work, its rules are different: they are in car expenses for autónomos.
How Facturaz handles it
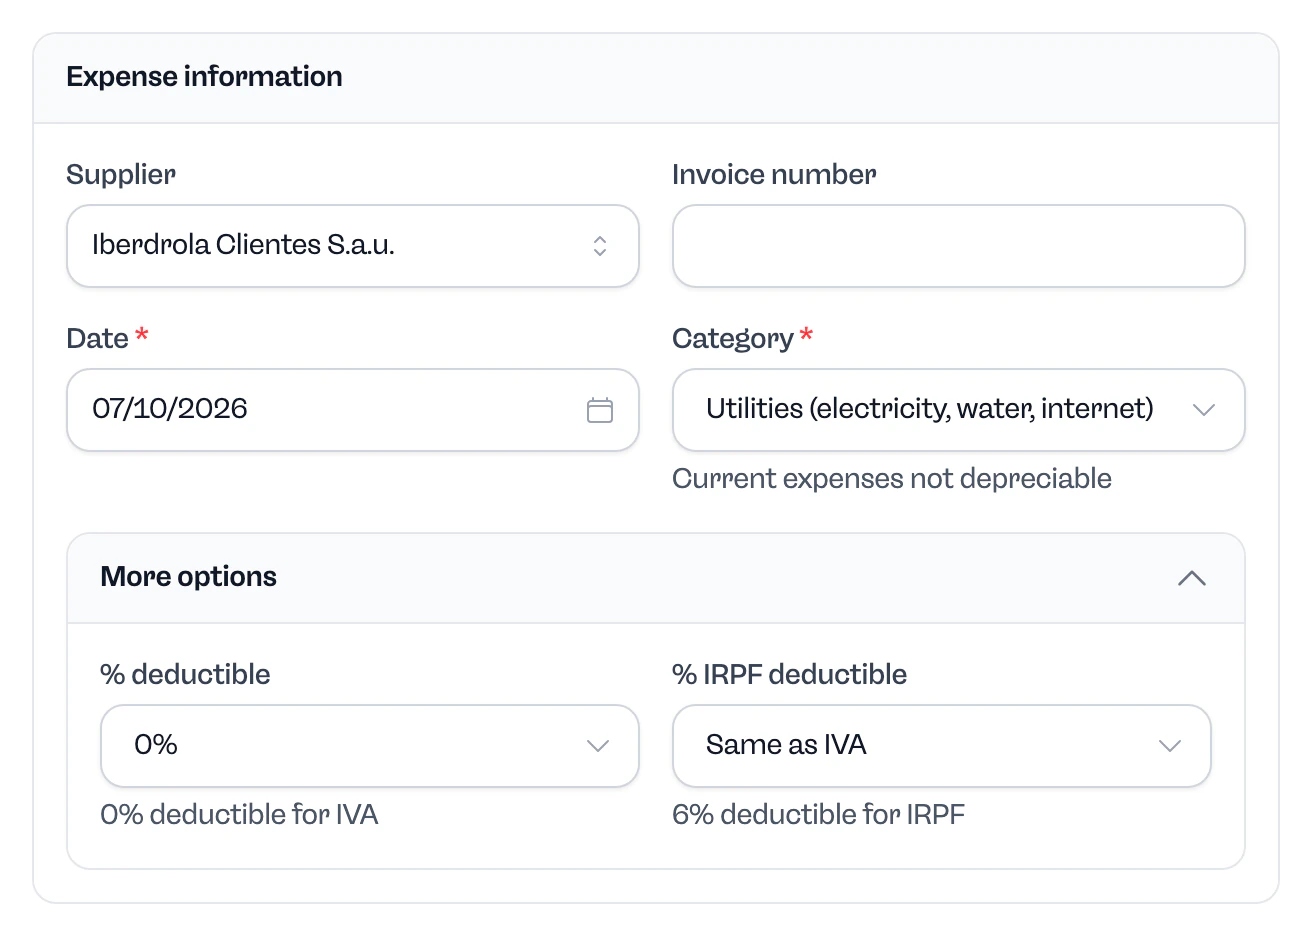
In Facturaz you take a photo of the bill and the AI fills in the supplier, date, base, IVA, total and category. In the utilities category the 30% home office share is applied for you. Autónomo Go costs €24 + IVA a month and Autónomo Plus €44 + IVA a month, with 14 days free, on Facturaz pricing.