An issued invoice is never deleted or edited. If it had an error, or the amount changes later, you issue another invoice that corrects it: the factura rectificativa (corrective invoice, often called a credit note). It is one of the basic rules of how to invoice as an autónomo, the guide that brings together everything an invoice must contain.
Here is when it is compulsory, what it must show, the two ways to issue it, the deadline and how it counts in your IVA (Spanish VAT) return. The rules come from article 15 of the Invoicing Regulation (Real Decreto 1619/2012) and articles 80 and 89 of Ley 37/1992 on IVA.
When you must issue a factura rectificativa
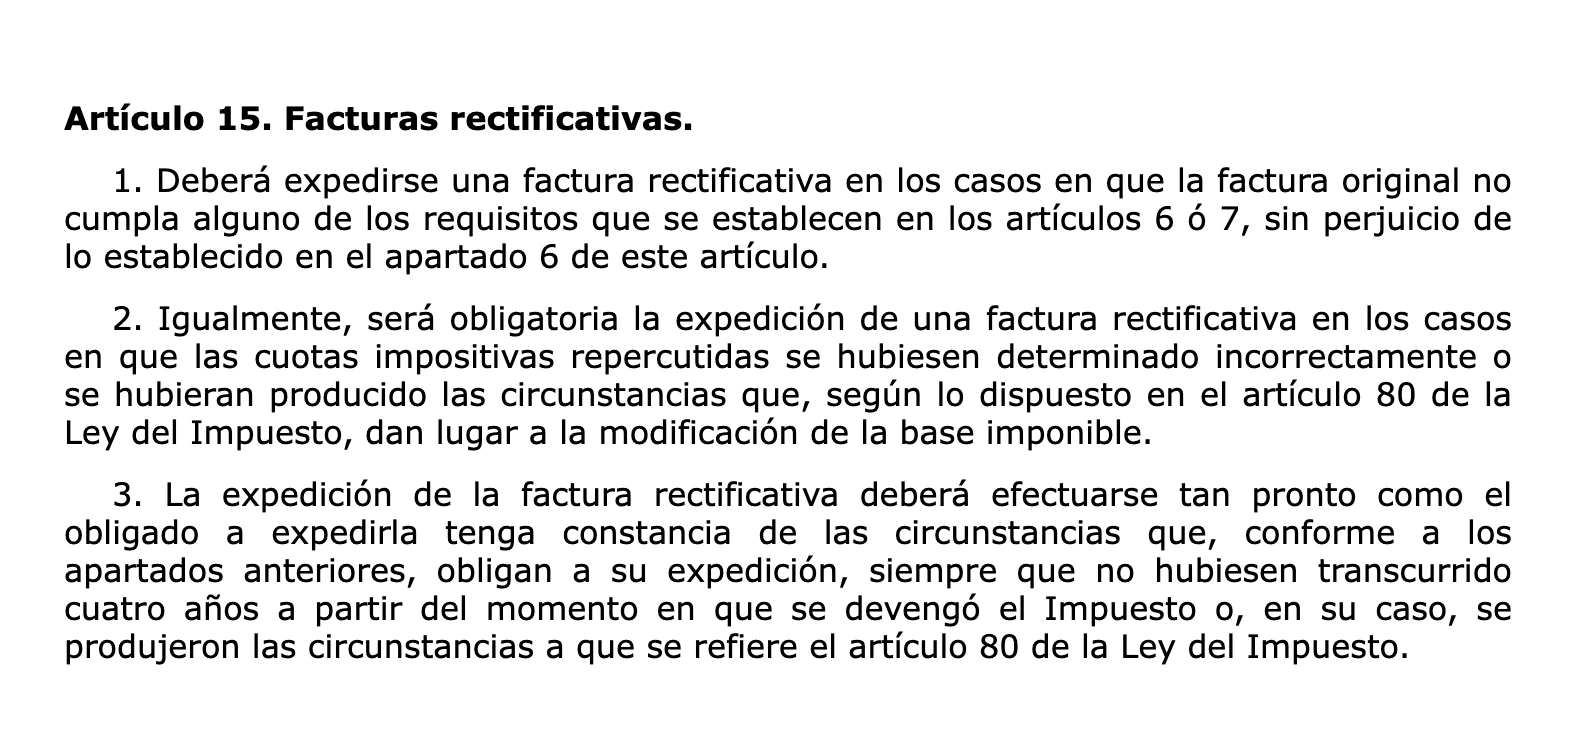
Article 15 of the Invoicing Regulation requires one in three situations:
- The invoice is missing a detail or has it wrong. For example your client's NIF (tax ID) or address, the description or the date. Any requirement in articles 6 or 7 of the Regulation counts (article 15.1).
- The IVA was calculated wrongly. You applied the wrong rate, charged IVA on an exempt operation or forgot to charge it (article 15.2).
- The taxable base changes after the sale for one of the reasons in article 80 of the IVA Law (article 15.2).
Only these reasons make an invoice a rectificativa (article 15.6). So when a client asks for a full invoice in exchange for a factura simplificada (simplified invoice) that was correct, the new one is not a rectificativa: it is an exchange.
Changes to the base under article 80
The taxable base changes, so you must correct the invoice, in these cases:
- Reusable packaging is returned to you (article 80.Uno.1.º).
- You grant a discount or rebate after the sale, for example a volume rebate at the end of the year (article 80.Uno.2.º).
- The operation is cancelled in full or in part, or the price changes afterwards: a client returns a product or cancels part of an order already invoiced (article 80.Dos).
- Your client enters insolvency proceedings without having paid you (article 80.Tres).
- Your client does not pay and the debt counts as uncollectable (article 80.Cuatro).
If a client does not pay you
When you issue an invoice, you pay its IVA to the tax office even if you have not been paid. If the client never pays, you can recover that IVA with a rectificativa, but only if all these conditions are met (article 80.Cuatro of the IVA Law):
- One year has passed since the IVA accrued without payment. If your turnover in the previous year did not exceed €6.010.121,04, the period can be six months.
- The invoice is recorded in your IVA record books (libros registro).
- Your client is a business or a professional or, if it is a private individual, the invoice base is over €50.
- You have claimed payment through the courts, with a notarial demand or by another means that leaves reliable proof of the claim.
Once that period is over you have six months to issue the rectificativa. Then you have one month to report it to the Agencia Tributaria with the form on its online office, together with a copy of the rectificativa and proof of the claim (article 24.2 of the IVA Regulation). It is not possible if the client is not established in Spain, the Canary Islands, Ceuta or Melilla, except in insolvency proceedings in another EU country, nor for debts secured by property, guaranteed or insured, nor between related parties (article 80.Cinco).
The deadline: as soon as you know, within four years
You must issue the rectificativa as soon as you know the reason, provided four years have not passed since the IVA on the original invoice accrued or since the article 80 event happened (article 15.3 of the Invoicing Regulation and article 89.Uno of the IVA Law).
There is one limit worth knowing. If the correction increases the IVA because of your own error and your client is a private individual, you cannot pass the difference on to them. You can only do so when the reason is one in article 80 or a rise in IVA rates approved by law (article 89.Tres.1.º).
What a factura rectificativa must show
A rectificativa is an invoice like any other, so it carries the same details as a full invoice under article 6, or those of a simplified invoice under article 7 if you are correcting a simplified one (article 15.5). On top of that:
- Its own series. Corrective invoices go in a specific series, separate from your normal invoices (article 6.1.a). A common format is a letter in front, such as R-2026-0001.
- The details of the invoice you are correcting: its number, series and date (article 15.4). One rectificativa can correct several invoices if you identify them all. If the reason is a volume discount, stating the period it covers is enough.
- The correction you are making. The description, the base and the IVA amount express the correction (article 15.5).
Article 15 does not require you to state the reason, but one line such as "two units returned" or "client NIF corrected" helps your client record it.
By difference or by substitution
Article 15.5 lets you choose between two ways of showing the amounts:
- By difference: you show only the amount of the correction, with its sign, positive or negative.
- By substitution: you show the figures as they stand after the correction and also state the amount of the correction.
An example. Carmen, a designer, invoiced an agency €1.000 + IVA. Later they agree a €200 discount on that job. This is the rectificativa in each format:
| Item | By difference | By substitution |
|---|---|---|
| Taxable base | −€200,00 | €800,00 (correction: −€200,00) |
| IVA 21% | −€42,00 | €168,00 (correction: −€42,00) |
| Total | −€242,00 | €968,00 (correction: −€242,00) |
The tax effect is the same: the IVA you declare goes down by €42.
Returns with a new order
If a client returns goods or packaging and buys from you again, you do not need a separate rectificativa: you can subtract what was returned on the invoice for the new order, as long as every operation carries the same IVA rate (article 15.2, second paragraph).
Why an invoice is never deleted or edited
Numbering within each series must be consecutive (article 6.1.a). Delete an invoice and you leave a gap. Edit it and the document your client holds no longer matches yours. That is why the law always corrects with a new invoice that identifies the earlier one (article 15.4). If the whole operation is cancelled, the rectificativa shows the full amount as a negative.
Under Veri*Factu this is also built into your invoicing software: each invoice creates a record that cannot be altered without the system detecting it. Any correction is made with a new, later record (article 8.2.a of the Regulation approved by Real Decreto 1007/2023). Under the law in force, the software must be adapted before 01/01/2027 if you pay Corporate Income Tax and before 01/07/2027 in every other case, autónomos included (fourth final provision of Real Decreto 1007/2023, as amended by Real Decreto-ley 15/2025). The government has announced a delay to 2028, but it has not been published in the BOE: see Veri*Factu delayed to October 2028. The other requirements are in what Veri*Factu is and how to comply.
How it affects your modelo 303
Article 89.Cinco of the IVA Law depends on whether the rectificativa lowers or raises the IVA:
- If it lowers the IVA (a discount, a return, an unpaid debt or an error in your favour), you can subtract it in the modelo 303 for the period in which you make the correction or in later ones, up to one year afterwards. In that case you must refund your client the IVA you overcharged. The other route is to ask the tax office to correct the original return (article 120.3 of the General Tax Law).
- If it raises the IVA because of an error and the tax office has not asked you first, you file a corrective return for the period of the original invoice, with any surcharge and interest due. What that means is in surcharges for filing late. If the increase comes from an article 80 reason or a well-founded error of law, you can include it in the 303 for the period in which you correct it.
Your client, if it is a business or a professional, adjusts its IVA too. When the rectificativa lowers the IVA for an article 80 reason, such as a discount or a return, it subtracts that amount in the return for the period in which it receives it (article 114.Dos.2.º of the IVA Law).
How Facturaz does it
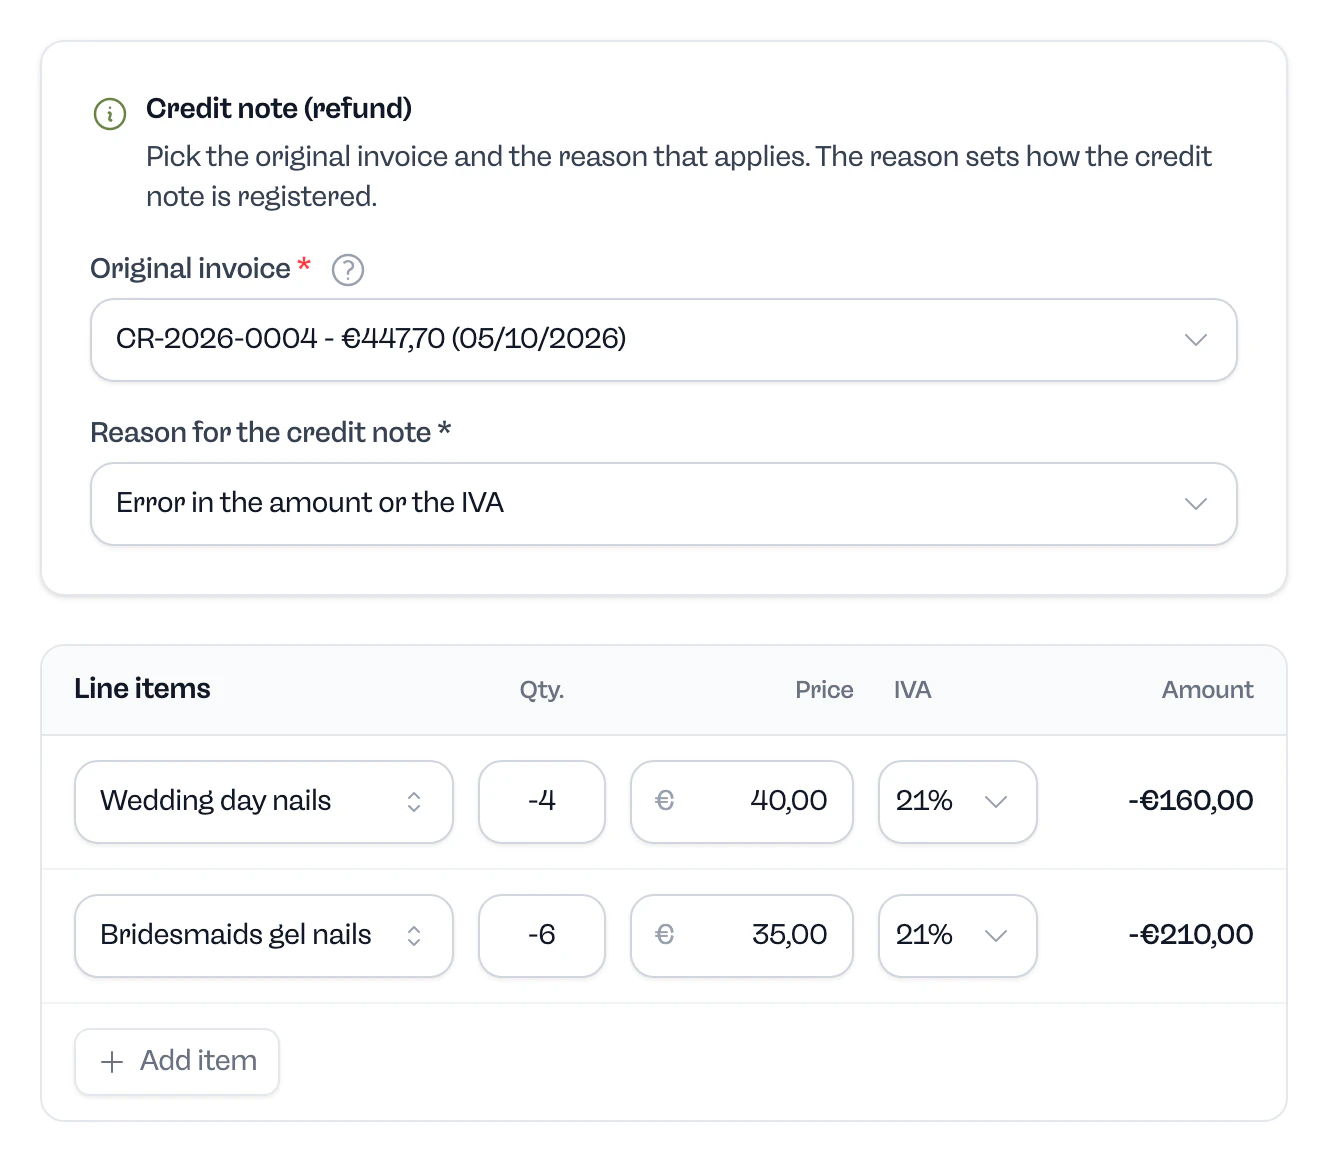
In Facturaz an issued invoice is never voided, deleted or edited. Every correction is a rectificativa that copies the lines of the original as negative amounts and references it. Facturaz is Verifactu compliant. Autónomo Go costs €24 + IVA a month and Autónomo Plus €44 + IVA a month, with 14 days free: see pricing.